Samsung Bets 6.7 Trillion Won on the New Semiconductor Chokepoint
Samsung Electro-Mechanics is making its largest-ever single-product capital investment in FC-BGA packaging substrates. The move signals that chip packaging, not fab capacity, is the new bottleneck in the AI chip race.
The bottleneck nobody’s talking about — yet
While the world watches who can build the fastest GPU, the real constraint in the AI chip race is a thin disc of woven glass and copper no bigger than a postage stamp. It is called a substrate, and Samsung Electro-Mechanics just bet 6.78 trillion won ($4.6 billion) that it will determine who wins the next generation of AI servers.
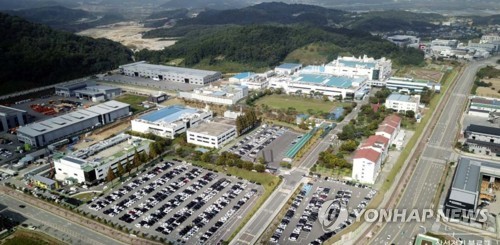
Samsung disclosed Thursday that it will invest 4.27 trillion won in a packaging substrate expansion at its Sejong facility in South Korea and 2.51 trillion won in its Vietnam operations. The Sejong investment alone is the company’s largest-ever commitment to a single product line. Mass production on the new lines is scheduled to begin in September 2028, following a construction window that runs through May 2028.
The product at the center of this bet is FC-BGA — flip-chip ball grid array substrate. It is the physical bridge between a high-performance chip and the motherboard, and it is becoming the narrowest passage in the entire AI supply chain.
Why packaging is the new bottleneck
Advanced chipmaking has long been a contest of nanometers. But as transistor scaling slows and designs grow more complex, the industry is hitting a different limit: you can print the smallest chip in the world, but if you cannot connect it to anything reliable, it is worthless.
FC-BGA substrates have to do something increasingly difficult. They route signals from AI accelerators, GPUs, and CPUs across many layers of copper and ceramic — sometimes more than thirty — while managing heat, power delivery, and signal integrity at speeds that barely make physical sense. The larger the chip and the more layers required, the harder these substrates are to manufacture at scale. Defect rates climb. Yields drop.
That is exactly the problem the AI boom has created. Demand for large-area, high-layer-count FC-BGA substrates has surged alongside the expansion of AI data centers. Every new GPU generation eats more substrate. Every chiplet-based design multiplies the problem.
Samsung’s answer is capacity. A lot of it. The company said it will use the Sejong site as its core hub for high-value, high-difficulty products aimed at AI servers and high-performance computing. Vietnam will serve as a supplementary node — a decision that also reflects the broader corporate strategy of diversifying away from over-concentration in any single country.
Who wins, who loses
TSMC currently controls the majority of advanced packaging revenue. Its CoWoS (chip-on-wafer-on-substrate) platform is the default route for leading-edge AI chips. Intel is trying to replicate that leadership through its IFS foundry model. Samsung Foundry sits in the middle. But on the substrate side — the passive component beneath the package — the field is less consolidated, and that is where Samsung’s bet lives.
The winners from Samsung’s expansion will be the AI chip designers who have been waiting for substrate capacity. Customers such as NVIDIA, AMD, and the custom silicon teams at Google, Microsoft, and Amazon have all complained publicly about packaging lead times. A well-timed influx of new substrate supply would ease one of the most invisible sources of delay in AI hardware delivery.
The losers are not obvious. Samsung Electro-Mechanics is not competing directly with TSMC on packaging services — they operate at different layers of the stack. But the investment does signal that Samsung sees substrate as a strategic moat worth protecting. If Samsung can lock in long-term supply agreements with the same big-tech customers TSMC courts, it gains leverage that extends beyond the balance sheet of its parent company, Samsung Electronics.
The timing tells the real story
The 2028 mass-production target is deliberate. Industry cycles for AI server chips run roughly two to three years between announcement and volume ramp. If Samsung starts shipping in late 2028, it will be positioned to supply the next round of GPU and accelerator designs that are being planned now for deployment in 2029 and 2030.
That is a long lead time for a capital project. It means Samsung is betting that demand will remain tight through the end of the decade — not that it will plateau after the current AI buildout. The company’s own language is telling: it framed the expansion around AI servers and high-performance computing specifically, not general-purpose semiconductors. This is a narrow, targeted wager.
The market is already pricing in some of the upside. Analysts raised Samsung Electro-Mechanics’ third-quarter operating profit forecast to 650 billion won from 600 billion won, citing the strength of long-term supply contracts with global big-tech firms even as the won-dollar exchange rate moved against them. Currency headwinds should have compressed margins. Instead, the contract book appears to be insulating the company.
What this says about the AI hardware race
The most important implication of Samsung’s investment is not financial. It is structural. For years, the narrative around AI chip supply chains focused on fabrication: who has the most advanced node, who can produce the most TSMC-equivalent capacity, who can win EUV lithography access.
But as chip designs grow larger and more complex, and as chiplet architectures fragment the workload across multiple dies, the packaging layer is becoming the limiting factor. You can have the best process node in the world. If your substrate supplier cannot deliver enough high-layer boards at yield, your chip does not ship.
Samsung is treating this constraint as a commercial opportunity. That is not trivial. Substrates are not glamorous. They are heavy, require expensive materials, and have long development cycles. But they are essential, and they are hard to substitute. Whoever controls sufficient substrate capacity at the right time controls a chokepoint.
The 6.78 trillion won commitment says Samsung intends to own that chokepoint — or at least to carve out a defensible share of it. Whether it succeeds will depend on whether the company can hit its 2028 ramp, maintain yield on increasingly complex substrates, and lock in contracts before the market fills up again.
The AI chip race is no longer just about who builds the fastest transistor. It is about who can assemble the fastest chip. And Samsung is placing a very large bet on the answer.