Cook's AI Inflation Warning Upends Fed Rate Outlook
Fed Governor Lisa Cook publicly linked the AI boom to near-term inflation pressure — a rare narrative shift that complicates the central bank's path and rattles rate-expectation models across global markets.
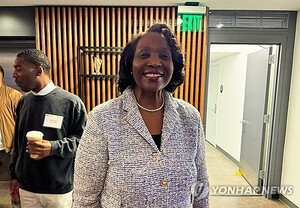
The narrative just shifted under the Fed’s feet.
Lisa Cook didn’t mince words at Oakland Tech Week on January 28. She confirmed what many macro strategists have been quietly flagging: the artificial intelligence boom is not the disinflationary miracle the market has been pricing in. In the near term, AI is a tax on prices. The relief — if it comes — is a distant promise.
Cook said she still expects AI-driven productivity gains to deliver “gradual disinflation” over the coming years. But those gains, she warned, will not arrive soon enough to offset the inflation pressures building right now. That timing gap is the story. And it is a story the Federal Reserve has rarely told this plainly in public.
Who cooks the books now — and who pays the bill
The immediate implication is blunt. If AI infrastructure buildout — data centers, energy grid upgrades, chip fabrication, cooling systems, and the surrounding real-economy inputs — is pushing against headline inflation, then the productivity dividend that economists have modeled into every base-case scenario is delayed. Markets that priced a smooth march back to the 2 percent target may be looking at a bumpier road.
Cook pointed to a confluence of pressures. AI capex is real and accelerating. Oil prices are lifting off on Middle East supply risk. Supply chain frictions persist. Taken together, these factors create a policy puzzle that does not resolve itself with another rate cut.
And Cook voted for a rate hike at this month’s FOMC meeting, joining eleven other voting members in tightening rather than easing. That vote matters less than the reasoning behind it — she made clear the decision was conditional on data, not dogma. Still, a governor publicly anchoring the case for restraint while the AI investment cycle is at its hottest send a signal that the Fed is watching the wrong narrative.
The labor-market trap Cook flagged
Perhaps the most consequential part of Cook’s remarks was not about inflation at all. It was about unemployment — and the awkward place the Fed would find itself if AI-driven labor displacement pushed the jobless rate higher without delivering the productivity gains needed to justify lower rates.
Cook said she is monitoring a scenario in which AI temporarily raises the unemployment rate, but emphasized that the increase would likely reflect a skills mismatch on the supply side rather than a demand-side collapse. Workers being displaced from certain roles are not automatically slotted into the ones AI is creating. That distinction matters because it changes the Fed’s tool kit.
If unemployment rises because demand has fallen, rate cuts are the conventional response. If unemployment rises because of a structural mismatch, rate cuts do very little and may instead fan inflation. Cook was explicit about the dilemma: cutting rates to lower unemployment could reaccelerate price growth. In that world, the Fed’s levers are thin.
This is not a theoretical concern. Several major U.S. employers have already announced workforce reductions tied to AI automation. The macro data on those displacements has not yet appeared in labor-market aggregates, but the leading indicators are flashing. Cook’s warning is an early official acknowledgment that the labor market may not absorb the transition cleanly.
What this means for rate expectations heading into 2027
The market consensus has been leaning toward a gradual easing cycle, with most models assuming inflation cools as productivity improves. Cook’s speech fractures that assumption at the margins. If her timeline is right — disinflation arriving after the near-term pressure peaks — the Fed may need to hold rates higher for longer than investors expect, or even revisit tightening if inflation proves stickier than modeled.
That is a significant reweighting of probability. Options markets and treasury yields will repricing this. The 2-year and 10-year curves are sensitive to exactly this kind of narrative shift, and Cook just gave traders a new variable to plug into their models.
For global markets, the spillover is real. The dollar tends to strengthen when U.S. rate expectations rise. Emerging-market debt becomes more expensive to service. Commodity importers face a tougher financing environment. And if AI-capex-driven demand pushes energy and materials prices higher, the pass-through to global inflation spreads faster than anyone wants.
Why this lands harder than a typical Fed comment
Governor Cook did not announce a policy pivot. She reiterated a data-dependent stance. But the framing is new. Central bankers have historically treated productivity shocks as exogenous — something that arrives and either helps or hurts without warning. Cook treated it as endogenous: an investment cycle that generates its own inflation before it generates its own relief.
That reframing is significant. It means the Fed is now explicitly acknowledging that the single biggest technological investment cycle in decades is operating as a near-term inflationary force, not a long-run benefit waiting in the wings. If other governors pick up this language, the institutional narrative shifts quickly.
Cook also tied the AI-inflation link to a concrete operational concern — the mismatch between when inflation shows up in the data and when productivity shows up. That lag is the gap where policy mistakes happen. It is also the gap where the Fed loses credibility if it acts too early or too late.
The read-through for investors
Three things follow from this speech.
First, rate-cut expectations for the next two FOMC meetings should be priced more cautiously. Cook’s language supports patience, not reversal. The bar for easing has just risen.
Second, sectors that benefit from sustained higher rates — certain financials, parts of insurance, and businesses with strong pricing power — may find their fundamentals reinforced rather than threatened by the AI-inflation story. Sectors dependent on cheap capital and multiple expansion face headwinds.
Third, the labor mismatch angle deserves closer monitoring. Cook’s scenario is not a recession forecast. It is a stagflation-adjacent warning: slower job creation in displaced sectors, sticky inflation, and limited monetary response. That combination rewards resilience and penalizes leverage.
Cook did not come to Oakland to scare markets. She came to update them. The Fed’s AI-inflation timeline is now an official variable in the policy equation — and the sooner investors adjust their models, the fewer surprises await them in the data that follows.