The Nvidia Feud That Exposes Who Controls U.S. Chip Policy
A public clash between Trump's Commerce and Treasury secretaries over Nvidia chip leaks to China reveals who really holds America's semiconductor chokehold — and whether tech-decoupling survives its own internal contradictions.
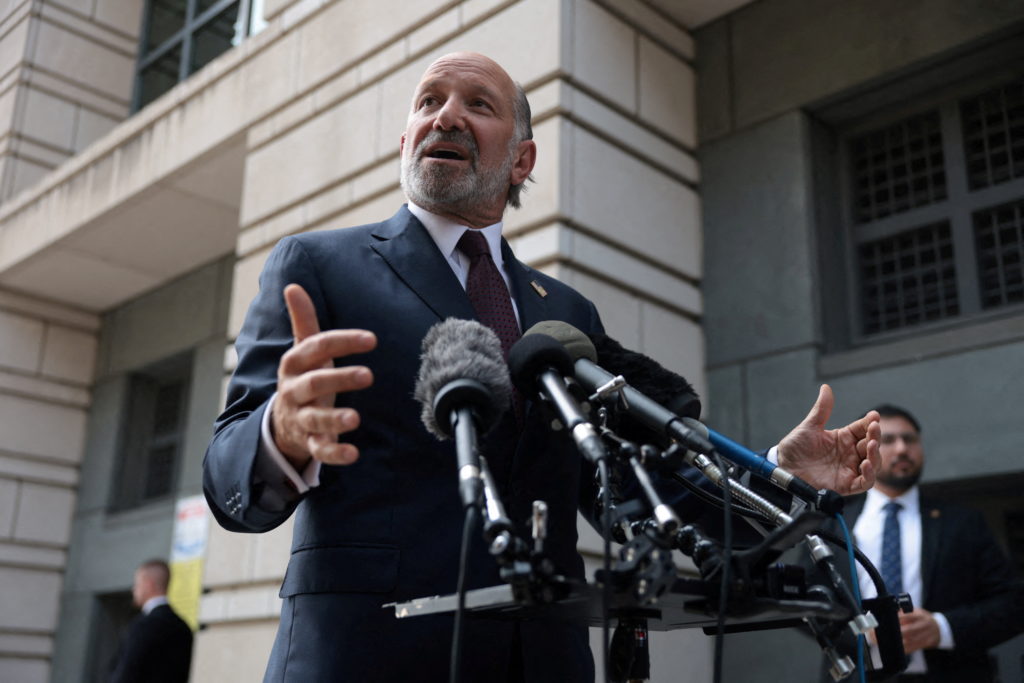
The Feud
Two of President Donald Trump’s top advisers — Scott Bessent, treasury secretary, and Howard Lutnick, commerce secretary — turned an internal administrative fight into a public one on CNBC last week. Bessent accused Lutnick of willfully looking the other way while China obtained Nvidia’s most advanced chips through a Singapore-based middleman called Megaspeed. Lutnick did not respond directly on air but has spent the past year positioning himself as the administration’s champion for keeping American technology accessible to Chinese buyers. Where the clash lands will reshape export-control policy, U.S.-China tech strategy, and the global semiconductor supply chain.
Who Controls the Chokehold
The simplest way to read the fight is as a bureaucratic turf battle. Lutnick’s Commerce Department administers the entity list and controls which countries and companies are banned from buying American technology. Bessent’s Treasury brings war, USTR, and State along whenever it pushes to put someone on that list. Last year, Treasury had been in favor of putting Megaspeed on the entity list for months. Commerce has the pen. When the regulation finally stalled, Bessent took it personally on air.
But the deeper question is who really controls America’s semiconductor chokehold. For years, the executive branch has argued that restricting Chinese access to cutting-edge chips is the single most effective lever against Beijing’s military and AI modernization. That argument began when the administration first blocked Huawei from buying semiconductors with American content. It carried through into the next term. The logic is blunt: each generation of chips lost buys the United States time against a competitor that now treats technological self-sufficiency as existential.
The tension sits at the heart of today’s dispute. Lutnick sees a marketplace, arguing consumers want access to the stack. Bessent sees a leak, flagging pass-through shell companies that might be diverting restricted hardware to unauthorized end users like Megaspeed. Both sides claim to love China economically. One argues that loving it means selling to it. The other argues that selling to it means losing leverage.
The Megaspeed Case
All the blame has centered on a company called Megaspeed, a Singapore-based distributor whose leader reportedly maintained close ties to Jensen Huang during the period when restricted chips were flowing. Whether Lutnick’s Commerce Department enforced rules or looked away remains unclear. But a pattern has emerged: H100-class and newer chips kept reaching China through intermediaries despite regulatory barriers, and a timeline has crystallized around when those barriers supposedly should have held.
In early 2025, the previous administration pushed through new regulations requiring most foreign companies to get Commerce Department permission before buying advanced chips. They lasted two days before Commerce said it was suspending enforcement. If the department had followed through, Megaspeed could not have bought whatever it wanted. Because it didn’t, the middleman kept operating uninterrupted. Chris McGuire of the Council on Foreign Relations — formerly director of technology on the National Security Council staff under President Joe Biden — summarized the damage plainly to PBS:
While poor implementation on export controls has probably cost us years of advantage, doubling down now will still give us years, even potentially decades of advantage in the future, as long as we actually manage it right. But if we don’t, China is going to stay close and that will have catastrophic impacts for U.S. national security.
Huang’s Role
Where the fight becomes truly awkward is around Jensen Huang, Nvidia’s CEO, who has enjoyed celebrity status in China and maintained a personal relationship with Lutnick throughout the administration. Huang reportedly told PBS that America should win at every layer, including the chip layer, rather than concede the Chinese market entirely. He framed opening China as essential to Nvidia’s global competitiveness and argued that restricting sales would hand Beijing an opening.
McGuire pushed back sharply in the same interview:
Well, Jensen certainly wins if they sell chips to China, but I would argue America does not win.
The disagreement captures the fundamental fracture running through U.S. policy. One side treats Chinese demand as a revenue stream worth protecting. The other treats it as a vector for technological transfer worth blocking. Neither side questions that chips matter. Both sides disagree about whom that judgment serves.
The Second-Order Effects
The public feud will empower advocates of stricter export controls on Capitol Hill. Legislators who previously argued for softer enforcement now point to the Megaspeed case as proof that voluntary compliance no longer works. Expect a push this session to tighten review thresholds, expand the entity-list process, and force companies to disclose end-user certificates for high-performance chip transactions. The political math favors hawks: each leaked chip becomes evidence that the prior standard was too soft.
Markets will react asymmetrically. Nvidia shares may dip on headlines about reduced Chinese revenue but rise on expectations of tighter domestic demand. Semiconductor distributors that relied on the Singapore pipeline will scramble to find compliant channels. Foundries in Taiwan and South Korea will face pressure to certify whether their output reaches restricted end users. Every player downstream of design will adjust pricing, contract terms, and customer lists. The reshuffle will ripple through the entire value chain.
Who Wins, Who Loses
If the enforcement campaign tightens, the Chinese AI industry loses access to the fastest silicon available from American vendors. Chinese developers currently rely on smuggled or diplomatically negotiated replacements, and each generation of restriction slows training pipelines. That slowdown compounds. Researchers observe that Chinese models now trained without cutting-edge chips fall further behind every quarter. The lag widens into structural disadvantage.
American chipmakers gain short-term certainty but lose part of their largest fast-growing market. Revenue from China has declined steadily over the past eighteen months, and further tightening accelerates the trend. Companies that once treated Chinese sales as growth drivers begin pricing them as risk adjustments. Distributors that relied on the Singapore corridor look for alternative channels. Foundries that built capacity around serving Chinese customers recalibrate output plans. The contraction feeds compounding effects.
Lutnick retains Cabinet standing but risks being viewed as the official who let enforcement slip. Bessent emerges as the architect of a harder line, claiming ownership over a more restrictive posture. Huang keeps media presence and diplomatic access but faces scrutiny over whether his company enforced end-user certification. None of the principals can claim clean hands. Each carries responsibility for part of the outcome.
What Stays Broken
Where the policy fails is at the enforcement seam. Treasury wants mandatory end-user verification for high-performance transactions. Commerce wants flexibility for distributors navigating gray markets. Both agree that unrestricted flow is unacceptable. They disagree about what threshold qualifies as restricted.
The disagreement recurs across jurisdictions. Export-control standards shift slowly through treaty bodies and regulatory processes. China’s Ministry of Industry treats chip scarcity as an engineering problem solvable by domestic investment. Every attempt to tighten American enforcement meets workarounds in third countries and parallel import networks. Sanctions regimes multiply but compliance gaps widen faster. Each new rule meets evasion by design.
The fracture cuts both directions. America loses revenue to competitors who don’t enforce. China loses speed because alternatives carry latency and licensing costs. Third countries profit from routing fees but attract scrutiny over transshipment. Every actor gains something and forfeits something else. The imbalance reproduces itself quarterly.
The Long Arc
What endures is the recognition that chips constitute strategic infrastructure. Nations now treat semiconductor access as equivalent to energy independence. Each generation of delay becomes measurable in training runs saved or lost. The metric shifts from gross domestic product to aggregate compute cycles per capita.
The internal feud proves that choking off a competitor requires domestic coordination. Dividing rivals demands alliance management. Restricting suppliers needs interagency discipline. The three cannot operate separately. Where one fails, the others erode.
The public clash shows that enforcing limits requires homegrown consensus. Splitting coalitions asks trust renegotiation. Tightening filters needs regulatory teeth. The pieces do not fit together cleanly yet.