NVIDIA's Record Earnings Won't Lift NVIDIA—It Lifts Its Supply Chain
NVIDIA is expected to post record Q2 results, but history shows its own stock rarely rises on the news. The real upside is in the ecosystem—LG, Doosan, and other Korean suppliers positioned to benefit.
The Paradox of NVIDIA’s Popularity
NVIDIA is preparing to report what LS Securities expects to be another record quarter—$91.9 billion in revenue, $2.08 in earnings per share, both toppling previous peaks. The market is bracing for numbers that reinforce the narrative that AI infrastructure spending is not slowing down. Big tech continues to write enormous checks.
But here is what most English-language analysts miss: NVIDIA’s own stock has not benefited from its own good news, not since the earnings party stopped being a party.
Over the past eight quarters, NVIDIA posted strong results seven times. The stock rose after only one of those reports. The pattern is not a blip. It is a structural feature of a company the market has already priced as the monopoly winner, where every milestone becomes a ceiling rather than a catalyst.
What changes the calculus is not NVIDIA itself. It is what NVIDIA’s cash flow means for everyone else in the room.
Who Actually Wins
The argument, laid out by LS Securities researcher Hwang San-hae, is straightforward but underappreciated by global desks. When big tech expands capital expenditure, the immediate beneficiaries are NVIDIA and memory makers. When NVIDIA itself generates massive free cash flow and profit, the secondary wave flows to the firms that supply it.
Think of it as a ripple moving outward from the center. The center gets the glory. The rings get the volume.
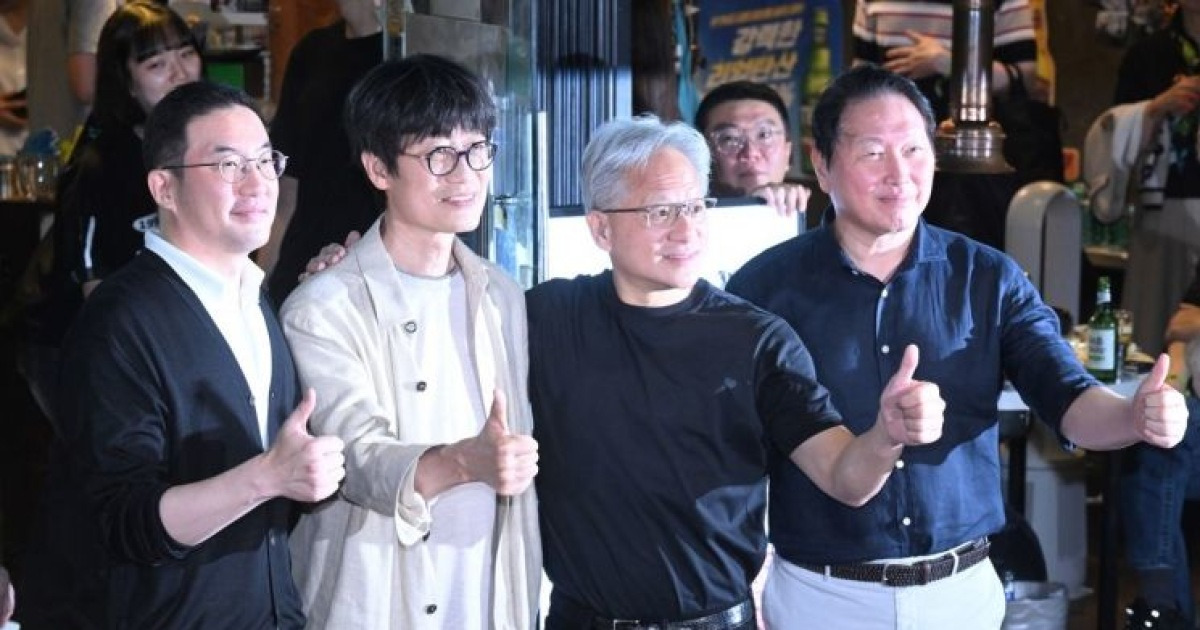
In Korea, that ripple is already visible. LG Group and Doosan Group have been the most prominent names linked to NVIDIA’s ecosystem in recent months, and not just by coincidence. Jensen Huang visited Seoul in June and met with top executives from SK, LG, and Naver. That kind of meeting does not happen without a strategy behind it. LG’s involvement spans cooling systems through LG Electronics’ CDU unit, CNS data centers, and LG Innotek’s robotics and sensor businesses. Doosan’s exposure runs through Doosan Energy Capability’s nuclear and gas turbine operations, Doosan Robotics, and its semiconductor equipment division.
The full list LS Securities flagged this morning includes Hanmi Semiconductor (equipment), Hyundai Mobis (robotics), Hyundai Engineering and Daewoo Engineering (construction), LS Electric (power equipment), and Samsung SDS (software). These are not speculative picks. They are companies with contracts, revenue visibility, and in some cases, board-level relationships with NVIDIA’s leadership.
Why This Matters Beyond Korea
The Korean angle matters because the country sits at a critical junction in the AI hardware supply chain. It is not just about memory chips—the DRAM and NAND story is already well known. It is about the infrastructure that makes those chips usable: cooling, power distribution, robotics for manufacturing, software stacks for data centers. NVIDIA designs the GPU. Someone has to keep it from melting, someone has to move it into place, someone has to wire it into a functioning building.
That is where LG, Doosan, and their peers earn their share. And as NVIDIA’s margins expand, the absolute dollar amount flowing to each link in that chain grows too. A 70 percent gross margin means a lot of spare cash to distribute—or at least, a lot of incentive for suppliers to capture a piece of it.
This is the part of the story that gets compressed in standard earnings coverage. The headline will be NVIDIA’s number. The investment implication is buried in footnote tables and Korean-language research notes. English-language readers rarely see it until the market has already moved.
Second-Order Effects Are Already Compounding
The ripple effect extends further than the direct supplier list. LG Electronics’ CDU business, for example, does not merely benefit from NVIDIA’s current design cycle. It is being integrated into next-generation liquid cooling architectures that will become standard as chip densities push air cooling past its breaking point. This is a multi-year positioning play, not a quarterly windfall. Once a cooling solution is qualified in a data center design, switching costs are high—both financially and operationally. That creates durable revenue visibility that extends well beyond any single earnings report.
Similarly, Doosan Robotics is moving into precision handling for AI chip assembly and testing, a niche that scales with every new fabrication node. Hyundai Mobis, traditionally an automotive parts maker, is pivoting robotics and automation capabilities toward semiconductor facilities. These are not pivot stories. They are diversification plays backed by existing engineering capacity, and they compound quietly as NVIDIA’s production volumes rise.
There is also a lesser-discussed effect on Korean construction firms. Hyundai Engineering and Daewoo Engineering are not simply building data centers—they are embedding NVIDIA-designed infrastructure from the ground up. That means deeper margins, longer contract cycles, and a competitive moat against international engineering firms that lack this level of integration. Every new facility accelerates their order books.
What Could Go Wrong
There are three risks to watch, all of which LS Securities flagged.
First, macro headwinds. Sustained pressure on U.S. long-end interest rates, a shock to retail sales, and ongoing uncertainty around the Middle East create an environment where even stellar earnings can be dismissed as irrelevant. If the market is worried about a slowdown, NVIDIA’s profit will not reassure it.
Second, margin compression. The expectation that NVIDIA’s profitability can keep climbing is baked into the current valuation. Any sign that additional margin expansion is limited would reinforce the “good news is priced in” dynamic that has haunted the stock for quarters.
Third, concentration risk. The Korean suppliers identified here are small-cap relative to NVIDIA. Their stock movements are louder and more volatile. A single contract win or loss can move a name significantly, which makes the thesis exciting but also fragile.
A fourth risk deserves mention: export controls. Any tightening of U.S. restrictions on AI chip sales to China could compress NVIDIA’s addressable market and, by extension, reduce the volume flowing through the supply chain that these Korean firms depend on.
What Happens Next
NVIDIA reports on August 27. The market will focus on the top-line number and guidance. The supply chain plays will move on what the number implies for their own revenue streams, not on NVIDIA’s headline result.
For global investors, the takeaway is simple: NVIDIA’s earnings are a proxy for AI infrastructure demand, but they are not the only place to express that bet. The real alpha in this cycle may not come from the chipmaker. It may come from the companies that build around it.
The question is whether the rest of the market realizes that yet. In Seoul, at least, some people are already trading accordingly.