What Musinsa's IPO Means for Korea's Retail Future
Musinsa's KOSPI listing bid reveals the tension between platform economics and profitability in Korean fashion e-commerce — and what the valuation gap says about investor appetite.
The 2 trillion won gap
Musinsa knows its worth: 10 trillion won, according to internal calculations. The market expects closer to 8 trillion won. That 2 trillion won discount — roughly $1.5 billion — is the most revealing number in the company’s upcoming IPO.
It is not merely a negotiation tactic. It is a mirror held up to Korean retail-tect investors’ current mood: enthusiastic about traffic and engagement, deeply skeptical about margins.
Korea’s stock exchange accepted Musinsa’s application for pre-listing review on Sept 8, with Korea Investment Securities and Citigroup Global Markets named as joint lead managers. The company, founded in June 2012, now operates three major platforms — the marketplace-style Musinsa Store, the women-focused 29CM, and its own private-label brand Musinsa Standard — under one corporate roof. Co-founder Jo Moon-ho and 26 other insiders still control 54.2 percent of outstanding shares as the filing process begins.
From fashion store to infrastructure play
Musinsa’s pitch to investors has always been that it is not a retailer. It is an infrastructure layer for Korean fashion — a combination of search, community, and logistics that lets hundreds of smaller brands reach consumers without building their own distribution networks.
That distinction matters because it changes how you value the business. A traditional fashion retailer trades on inventory turns and margin per unit. A platform trades on take rates, network effects, and the economics of serving more sellers without proportionally more cost.
The model has worked at scale. Musinsa’s GMV has consistently ranked among the top e-commerce figures in Korea’s fashion segment, and its private-label brand has quietly become one of the fastest-growing house brands in the market.
But scale on a platform is not the same thing as profitability. The company’s revenue growth has decelerated into the low-20 percent range — respectable in absolute terms, but a far cry from the hypergrowth years that justified earlier private valuations. LS Securities analyst Oh In-a noted that the IPO process will force the market to scrutinize whether Musinsa can defend margins while maintaining that growth rate. The question is not whether the company can grow — it is whether growth translates into earnings.
The platform premium has a ceiling
Korean retail-tech has a track record of public listings that struggled to justify their private valuations. When Coupang went public in 2021 at a valuation near $50 billion, Wall Street was euphoric. Three years later, the market had re-rated the company sharply lower, and the debate over when, or whether, the business would deliver sustainable profitability remains unresolved.
Musinsa is entering a different market now. Korea’s own institutional investors — who will be the primary buyers of a KOSPI listing — have grown more sensitive to margin profiles after years of being burned by growth-at-all-costs narratives. The 2 trillion won gap between internal and market valuation reflects that shift in sentiment.
The listing process itself will widen that gap or narrow it, depending on the bookbuild. Korea’s pre-listing review examines both quantitative thresholds and qualitative factors: financial viability, management transparency, continuity of operations, and investor protection. Passing that review is the first hurdle, not the last.
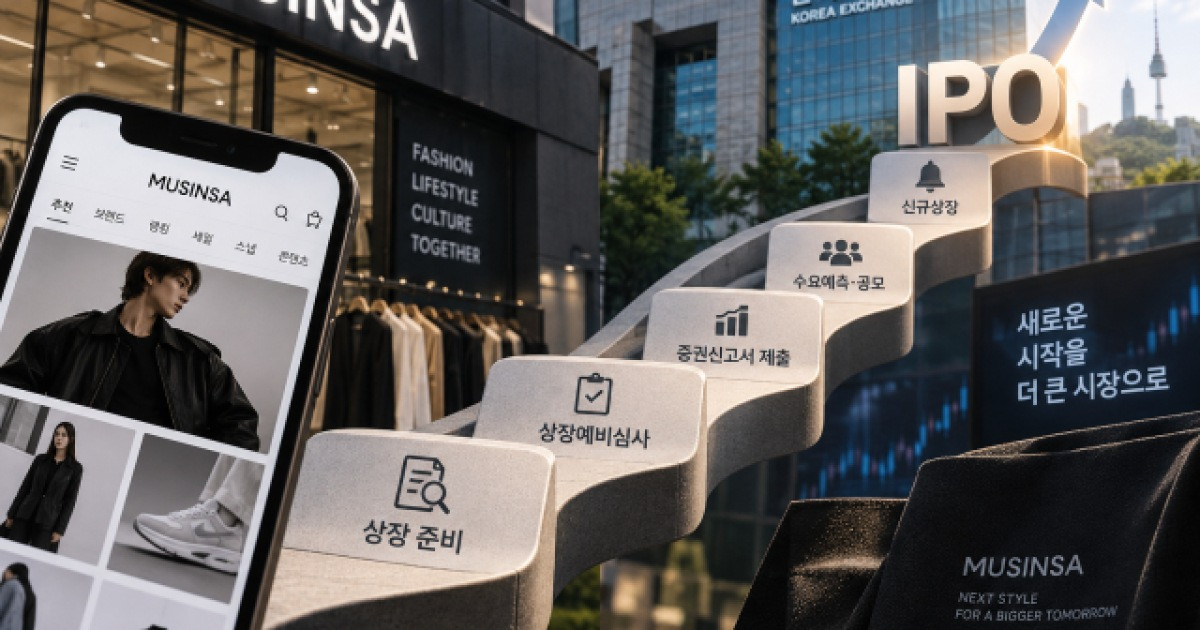
After the review, Musinsa must file a securities registration statement with the Financial Services Commission, conduct demand forecasting with institutional investors to set its offering price, open subscription to retail investors, and complete the final exchange listing procedures. The timeline, if things proceed smoothly, points to a first-half listing next year.
Who wins, who loses
The winning story is straightforward if Musinsa hits its targets: a domestically rooted platform, built for Korean consumer tastes, earns the kind of public-market legitimacy that typically goes to foreign-listed peers. For Korea Investment Securities and Citigroup, the deal would be a marquee assignment in a sector that has produced few recent large-cap Korean listings of comparable size.
The losing story is the one the market already seems to be pricing in. If Musinsa’s public results show margin compression alongside slowing growth, the 8 trillion won valuation target will look optimistic. The company’s 54 percent insider ownership gives founders considerable runway to resist short-term pressure, but it also means the market will have limited float to trade — a dynamic that can amplify volatility on the way down as much as on the way up.
What happens next
The real test comes after the stock starts trading. Platform businesses are judged not on a single earnings report but on the trajectory of unit economics over multiple quarters. Musinsa will need to show that its take rate from third-party sellers can hold or improve, that its private-label margins are expanding rather than eroding, and that 29CM can compete without subsidizing growth.
Korea’s consumer market is shifting again. Online fashion penetration has plateaued after the pandemic surge, and the competitive landscape includes both established players like eBay Korea and new entrants like TikTok Shop, which is testing cross-border fashion sales into Korea. Musinsa’s advantage is its localized supply chain and the brand equity it has built with young Korean consumers — advantages that foreign platforms struggle to replicate.
The listing process will reveal whether Korean investors are willing to pay a platform premium for a company that still carries the scars of a growth deceleration. The 2 trillion won gap is not just a number. It is the market’s current answer to that question.
Musinsa’s IPO has begun. The next chapter — whether the platform model earns its keep in public markets — is what will determine whether this listing becomes a milestone or a cautionary tale.