AI Sell-Off Meets Oil Surge: A Cross-Industry Repricing
The synchronized AI-stock selloff colliding with rising oil prices forces a cross-industry reassessment of capital expenditure, energy costs, and debt-fueled growth models. This is no longer just a tech story.
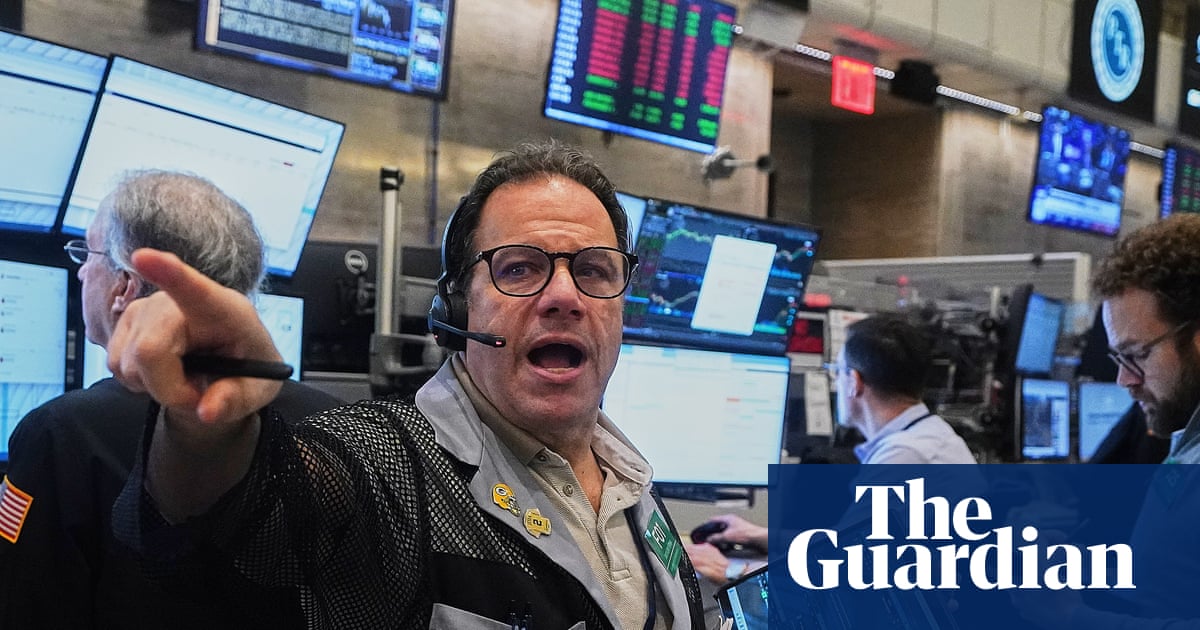
The Two-Front Shock
Thursday’s market move wasn’t just another tech correction. It was a collision between two independent shocks: a global reassessment of the AI capital‑expenditure boom and a spike in oil prices driven by Middle Eastern tensions.
The S&P 500 fell 1.2%, its worst day since July, while the Nasdaq tumbled 2.6%. Yet two‑thirds of S&P 500 stocks rose. The weakness in AI‑related equities was so overwhelming that it drowned out strength elsewhere in the market. The Dow Jones added a modest 11 points.
Oil tells the other half of the story. Brent crude leaped 4% to $113.17 a barrel, touching its highest level since May. Prices had started the month below $97, then rocketed on uncertainty over Iran’s war and its impact on global energy flows.
This combination—a broad sell‑off in AI‑related stocks alongside a sharp jump in oil—is rare. It signals that the market is repricing two narratives at once: the viability of the AI investment thesis and the risk of energy‑cost inflation. The ripple effects are already spreading beyond tech into semiconductors, autos, cloud infrastructure, and platform economics.
Who Wins, Who Loses
The immediate losers are the heavyweights of the AI ecosystem. Nvidia fell 4.4%, dragging the S&P 500 lower as the largest company by market value. Lam Research, which makes semiconductor‑fabrication equipment, reported profit and revenue that slightly beat analyst expectations—but its stock still tumbled 11.8%. Meta Platforms dropped 7% after reporting stronger‑than‑expected revenue but a profit miss, even as it announced a new class of stock to raise money for AI investments. Tesla fell 3.1% despite a profit beat, weighed down by weaker revenue. CoreWeave, a cloud‑chip‑rental company saddled with debt, fell another 10.1%.
Winners emerged in pockets. Procter & Gamble rose 5.6% after its CEO said the company stood by its full‑year growth forecasts despite “geopolitical and economic challenges.” Lockheed Martin and CSX also posted profit beats. Traditional energy names likely gained on the oil surge, though they weren’t highlighted in the data.
The pattern is clear: capital is rotating out of high‑multiple, high‑debt growth bets and into defensive, cash‑generating businesses. That’s a classic flight to quality—but it’s amplified by the energy shock.
The Ripple Through Semiconductors and Autos
The semiconductor‑equipment maker Lam Research is a useful case study. Its results were solid, yet its shares sold off. Why? Because the market is now pricing in two new variables: the cost of borrowing to build datacenters and the cost of energy to run them. Both have risen sharply.
Datacenter power demand from AI is enormous. When oil climbs, electricity costs often follow—especially in regions where power grids rely on natural gas or imported fuels. Higher energy bills squeeze datacenter margins and make AI capex less attractive. That’s why Lam’s stock fell despite a good report.
Tesla’s drop shows the autos industry’s exposure. Electric‑vehicle production is energy‑intensive, and higher oil prices can signal broader inflation that pressures consumer demand. Tesla’s revenue missed estimates, suggesting that even strong profits may not shield automakers from a cost‑inflation cycle.
Platform Economics Under Pressure
Meta’s decision to create a new class of stock to raise money for AI investments is telling. It acknowledges that the current funding model—burning cash on AI while hoping for future returns—is under stress. CoreWeave’s debt troubles highlight the same problem: borrowing to buy Nvidia chips and rent them out may no longer be a profitable strategy if energy and interest costs eat into margins.
Platform companies have built their AI dreams on cheap capital and cheap energy. Both are now more expensive. The reassessment isn’t just about whether AI will work—it’s about whether the economics of deploying it still make sense at higher cost bases.
Global Spillover
The AI sell‑off began in Asia. South Korea’s Kospi fell 3.5%, Hong Kong’s Hang Seng dropped 3%, and Japan’s Nikkei 225 sank 2.7%. These indexes are heavy with AI‑supply‑chain exposure: semiconductors, electronics, and cloud infrastructure. When the story goes global, the contagion is broad.
Europe felt a different kind of pain. France’s CAC 40 fell 1.4%, not from tech weakness but from surging French government‑bond yields. Violent protests and debt worries pushed yields higher, showing that fiscal stress can compound energy shocks. Meanwhile, US 10‑year Treasury yields fell sharply to 4.97% from 5.13% late Wednesday—a flight to safety as investors fled risk assets.
That divergence is instructive. US bonds became a refuge because the AI‑oil shock is primarily a risk‑asset event. Europe’s debt troubles remind us that energy price spikes can reignite fiscal vulnerabilities, especially in countries with already strained budgets.
What Happens Next
The immediate term‑out is volatility. AI stocks will remain sensitive to earnings reports, interest‑rate expectations, and oil‑price movements. The Nasdaq’s 2.6% drop suggests the sector is still finding its footing.
Medium‑term, the repricing will force strategy changes. Companies that relied on cheap debt to fund AI expansion may slow their capex or seek more efficient chip architectures. Energy‑intensive industries will face margin pressure unless they hedge costs or shift to lower‑carbon power sources.
Longer‑term, the AI boom may not die—but it will become more disciplined. The era of unlimited spending on datacenters and chips is likely over. Investors will demand clearer paths to profitability, and companies that can’t demonstrate efficient AI deployment may lose valuation multiples.
The two‑front shock of Thursday is a wake‑up call. AI is no longer just a technology story; it’s an energy story, a debt story, and a macro story. Markets are now pricing all three.
As Procter & Gamble’s CEO noted, “geopolitical and economic challenges” will continue. For AI investors, that means watching oil prices as closely as they watch earnings reports. The collision of capital and energy costs will define the next phase of the AI cycle—and who survives it.