Apple's Foldable iPhone Duo Changes the Premium Phone Game
Apple's iPhone Duo launch with oversized displays in four global stores marks a pivot point for the premium smartphone market. But supply constraints and a rushed pre-order strategy could complicate its rollout.
The Giant Displays Are a Signal, Not Just Marketing
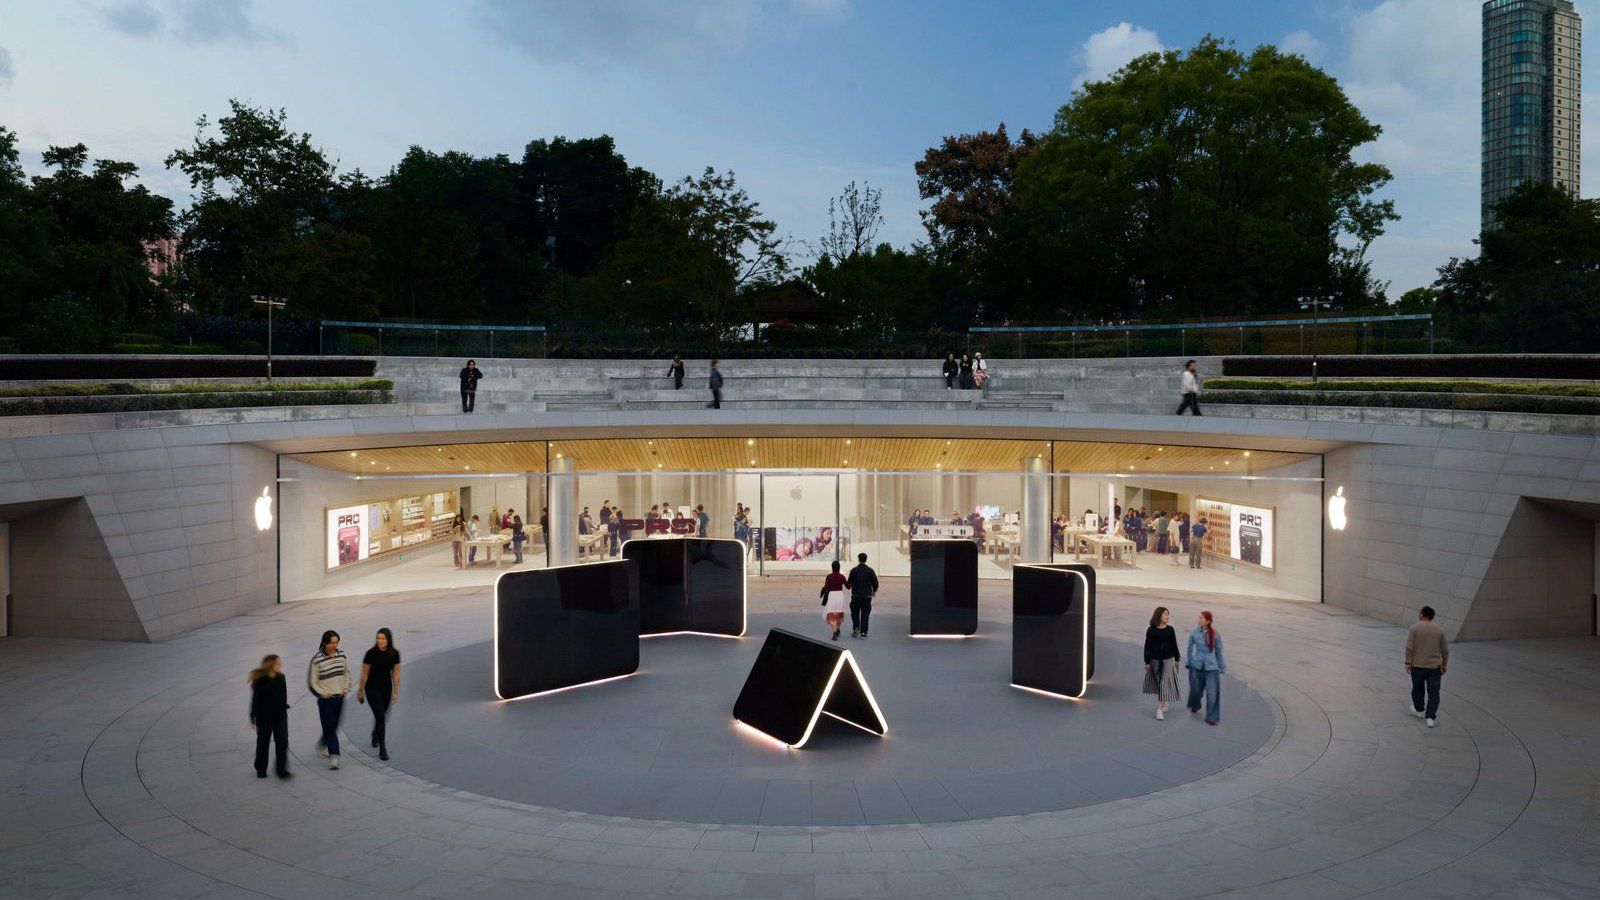
Apple doesn’t put 30-foot mirrored replicas of its phones in the middle of New York, London, Mumbai, and Shanghai unless it wants you to understand this isn’t just another iPhone year. The iPhone Duo’s launch Friday coincides with Apple’s boldest retail statement yet — four mega-displays in the world’s most visible commercial districts, each glowing with device “poses” that suggest Apple is redefining what a phone can be.
The installations were already shrouded and spotted by fans, but CEO John Ternus pulled back the curtain himself, posting a photo from Apple Jing’an on Weibo. The scale is deliberate. This is Apple telling the market: we’re no longer playing in the slab-phone sandbox.
What makes these installations particularly noteworthy is their permanence. Unlike temporary pop-up displays for seasonal product launches, these mirrored structures are mounted into the architecture of flagship stores, suggesting Apple views the Duo as a sustained category play rather than a one-year experiment. The reflective surfaces catch pedestrians mid-stride, literally forcing them to see themselves in relation to the device — a subtle psychological nudge toward ownership identity.
But the Real Story Is What Apple Almost Got Wrong
Here’s what the launch day choreography obscures: Apple is entering the foldable space with supply chain problems that nearly derailed the entire rollout.
Mark Gurman’s reporting cuts through the polished retail spectacle. Despite knowing the iPhone Duo would face “severe supply constraints” due to manufacturing challenges, Apple chose to open pre-orders on Friday instead of waiting until it had inventory ready. Gurman called it a “major mistake” in his Bloomberg newsletter, and he’s not wrong.
Opening pre-orders without inventory creates a specific kind of chaos. Customers pre-order. They show up on launch day. They discover there’s nothing to buy. Apple employees have reportedly been instructed to warn customers against visiting stores without pre-orders, essentially telling walk-in buyers to go home. Third-party retailers are experiencing the same strain, with some locations reporting frustration from customers who received confirmation emails but found shelves bare.
This is a self-inflicted wound. Apple’s retail empire has always relied on the experience — the genius bar, the instant gratification, the theater of unboxing a new device in person. Throwing cold water on launch-day foot traffic undermines that entire philosophy. More damagingly, it risks poisoning the well for a category where consumer patience is already thin. Foldable adopters have historically dealt with durability concerns and premium pricing; now they’re being told to wait longer.
Who Wins and Who Loses in the Foldable Arms Race
Samsung wins the patience game. The Korean firm has been shipping foldable Galaxy phones since 2019. It has iteration number seven or eight of its FlexForm factor, and it understands supply chain scaling for hinge mechanisms and flexible OLED panels. Apple’s missteps on pre-order timing are Samsung’s opportunity to lock in early adopters who can’t wait for Duo availability to resolve itself. Samsung’s Galáxy Z Fold and Flip lines are now approaching maturity in both form factor options and supply reliability, giving the company a window to widen its gap before Apple can scale production.
Chinese OEMs gain breathing room. Huawei, Xiaomi, OPPO, and Vivo all have foldable products on the market now at lower price points. Huawei’s Mate series XT line has been shipping for two years. OPPO’s Find N series offers competitive form factors at 30–40 percent lower prices than Apple’s expected premium positioning. Apple’s supply drama gives these players a window to expand their market share in regions where the Duo will arrive late or not at all. In China specifically, where Huawei has reemerged as a foldable contender with Kiric-enabled devices, Apple’s absence from shelves could shift perception that the Duo is an American import arriving on an American timeline rather than a global product.
Apple loses the first-mover narrative — temporarily. The iPhone Duo isn’t Apple’s first attempt at a new form factor (remember the Powerbook Duo?), but it is the company’s first true foldable phone. That distinction matters. When it ships, Apple brings its ecosystem advantage, app optimization story, and brand loyalty to a category where Samsung still struggles with software that treats folded devices as afterthoughts rather than first-class citizens. However, first-mover advantage in foldables has proven fleeting. Samsung shipped the first commercially viable foldable yet ceded significant mindshare to Chinese competitors who arrived with better pricing and faster iteration cycles. Apple’s delayed entry gives rivals two years of ecosystem maturation it must overcome.
The Global Rollout Problem
The four-store display strategy reveals Apple’s prioritization: New York, London, India’s BKC district, and Shanghai’s Jing’an. These are prestige locations, not indicators of simultaneous global availability.
BKC in Mumbai signals Apple’s intent to capture India’s growing premium segment, where foldable phones remain niche but aspirational. Jing’an in Shanghai acknowledges China as both a competitive battleground and a market where foldable adoption is already ahead of the curve.
But Gurman’s supply constraint reporting suggests these launch-day events may be largely theatrical. Limited walk-in availability means the stores will look impressive while empty. This is the tension Apple faces: the Duo demands a splashy launch to justify its category-defining positioning, but the manufacturing reality may not support it.
The rollout pattern also reveals something about Apple’s understanding of the foldable market. Unlike the iPhone, which ships globally on day one, the Duo’s staggered availability across regions creates a perception of inequality. Early reports from Shanghai suggest inventory is marginally better than other locations, potentially reflecting Apple’s willingness to prioritize the Chinese market where foldable penetration rates already exceed Western markets. This strategic choice could deepen resentment in markets perceived as secondary, even among loyal customers.
Second-Order Effects on the Industry
Apple’s missteps send ripples beyond the foldable segment. Supply chain analysts note that Apple’s pursuit of a thin hinge mechanism for the Duo is pulling demand away from components traditionally used in Samsung’s devices, creating short-term bottlenecks that could affect Galaxy production timelines. Conversely, display manufacturers now face competing demands: Apple needs ultra-thin flexible OLED panels with low crease visibility, while Samsung continues optimizing its third-generation Infinity Flex displays. The two companies’ engineering priorities are diverging, which could create entirely separate foldable display ecosystems rather than converging on a common standard.
App developers are already adjusting. The Duo’s aspect ratios and multitasking capabilities are forcing cross-platform teams to reconsider layout strategies, with some reporting that existing iPad apps require significant rework rather than simple upscaling. This development overhead falls disproportionately on smaller studios, potentially widening the gap between first-party Apple experiences and third-party alternatives — a dynamic that mirrors but amplifies the current foldable software problem.
Retail partners outside Apple’s direct stores face an uncertain landscape. Best Buy, Amazon, and regional carriers that traditionally rely on iPhone launch volume for quarterly targets now confront a product with ambiguous demand signals. If the Duo cannibalizes regular iPhone sales rather than expanding the overall premium market, those retailers face margin compression without volume relief.
What Comes Next
Apple’s mistake on pre-orders was logistical, but the underlying problem is structural. Foldable displays remain expensive to produce at scale. Hinge mechanisms add complexity that traditional iPhone assembly lines weren’t designed for. Yield rates are lower. Costs are higher.
Samsung learned this over half a decade. Apple is trying to compress that learning curve. It may work — the Duo’s app screenshots suggest software integration will be stronger than anything Samsung has shipped. But the launch period will be messy, and the market won’t wait for perfection.
The premium phone market is now bifurcating: foldables as a distinct category with their own supply constraints, design trade-offs, and consumer education challenges, versus traditional slabs continuing to improve with AI features and camera advances. Apple has just entered the first camp with enough brand weight to make it matter globally.
Whether Apple can sustain momentum past launch week depends on whether it fixes its supply chain faster than competitors exploit the gap. Samsung will be ready with updated hardware. Chinese OEMs will be ready with lower prices. The Duo’s success hinges not on its launch spectacle but on Apple’s ability to transition from theatrical announcement to reliable delivery — a discipline the company has mastered with iPhones but has not yet proven with a fundamentally new form factor. The mirrored displays may draw crowds, but only shipments will build the category.