China's Memory Chip Surge: Why CXMT's 60% R&D Boom Should Alarm Korea
Chinese DRAM maker CXMT nearly doubled its R&D headcount in a single year, closing the gap with SK Hynix to within 2,000 researchers. As CXMT claims double-digit DRAM market share and begins HBM production, Korea's memory dominance faces its most direct challenge yet.
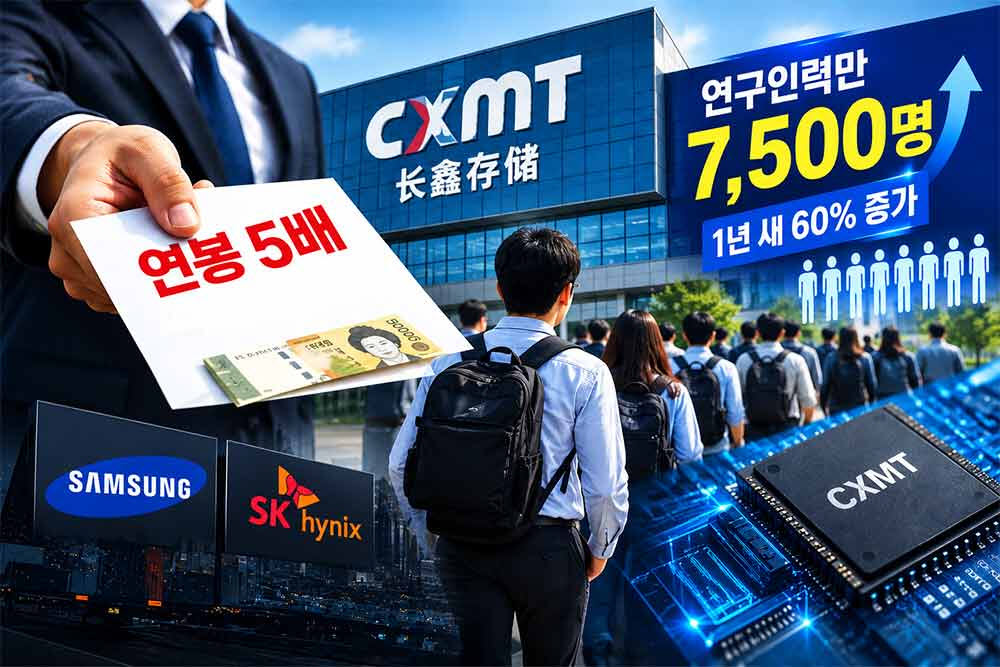
The Number That Should Worry Every Korean Fabless
Seven thousand four hundred ninety-one. That is how many researchers CXMT employed as of June 2026, up from 4,655 a year earlier — a 60.9 percent increase that tells you everything about where China’s memory-chip ambition is headed.
The gap between CXMT and SK Hynix, the world’s No. 1 DRAM maker, has collapsed to 2,160 researchers. SK Hynix added only 547 R&D staff over the same period, growing its headcount by 6 percent. In other words, CXMT is catching up faster than SK Hynix can grow. At this rate, the追赶 (zhui jian, or “chasing”) will not remain a metaphor for much longer.
What makes this figure genuinely unsettling is not the raw addition of 2,836 researchers — though that is substantial for a single company in a single year — but the composition and intent behind those hires. CXMT is not filling roles with junior staff waiting to learn on the job. The company is importing calibrated expertise at scale, targeting engineers who already understand what it takes to produce competitive DRAM at leading-edge nodes.
What CXMT Is Actually Building
Read the raw data and a pattern emerges. Two-thirds of CXMT’s researchers hold master’s degrees or higher. Ninety percent are under 40. Average compensation rose 34 percent year-over-year to 416,200 yuan per person, putting annual earnings on track to exceed 830,000 yuan — roughly 5.4 times the national average for senior technical professionals in Chinese state-owned enterprises.
This is not a barebones hiring spree. It is a deliberate, well-funded talent war. CXMT recruited across more than 180 positions on social media last month, explicitly targeting graduates from Chinese and overseas universities. The role mix is telling: AI researchers with PhD preference, engineers for electronic-design automation (EDA) tool localization — a capability China has long lacked and been blocked from acquiring through U.S. export controls.
Meanwhile, CXMT announced mass production of LPDDR6, the latest mobile DRAM standard, less than a year after JEDEC finalized the specification. According to the information technology publication The Information, the company also began small-scale HBM3E production. High-bandwidth memory for AI accelerators was once the exclusive domain of SK Hynix and Samsung. CXMT is now in the room.
The LPDDR6 milestone deserves particular attention. Memory standards typically take three to five years to move from specification to volume production, even for established players. CXMT’s acceleration suggests it is either leapfrogging conventional development timelines or benefiting from a compressed feedback loop between research and fabrication — likely both. The company’s Wuhan and Changzhou fabs, expanded significantly over the past two years, are producing wafers at densities and cycle times that would have been unthinkable a generation ago.
There is also the EDA question hanging in the background. American restrictions have blocked CXMT from purchasing the most advanced semiconductor design software from Cadence, Synopsys, and Mentor Graphics. Rather than stall, CXMT appears to be investing heavily in domestic alternatives, including tools from Empyrean Technology and other homegrown vendors. If those tools reach sufficient maturity, the entire strategic logic of export controls — forcing China to remain perpetually a step behind — unravels. That outcome is not a given, but it is no longer inconceivable.
The Market Share Math
Counterpoint Research places CXMT’s global DRAM revenue share at 10 percent for Q2 2026, up from 4 percent a year earlier. This is the first time the Chinese maker has broken into double digits. For context, fifth-ranked Taiwan’s Nanya sits at roughly 2 percent — one-fifth of CXMT’s position. CXMT has effectively leaped over at least two competitors in a single year.
These numbers are startling because Chinese memory companies have historically been stuck in commodity-grade, mature-node DRAM. Moving into LPDDR6 and HBM3E signals that CXMT’s process expertise is advancing faster than most outside analysts expected. The leap from 4 percent to 10 percent market share in 12 months is not incremental growth. It is a structural shift.
Consider the supply-side dynamics. CXMT’s growth is not being driven primarily by subsidized pricing or state procurement mandates, though those exist. The company is capturing share in commercial markets — smartphone makers, PC manufacturers, and server builders who are evaluating cost, yield, and performance on merit. That distinction matters. Subsidized displacement is fragile; market-driven displacement is durable.
The financial engineering supporting this expansion is equally notable. CXMT has tapped Beijing’s integrated circuit industry fund — commonly referred to as the Big Fund — for multiple rounds of capital. The second phase of the fund, approved in 2024, allocated roughly $47 billion toward semiconductor self-sufficiency. Memory chips received an outsized share of that allocation, with CXMT among the primary beneficiaries. The company’s balance sheet now carries significant debt, but in the context of Chinese industrial policy, that is almost beside the point. The objective is technological sovereignty, not near-term return on equity.
Why Korea Cannot Sleep
Han Yang University professor Baek Seok-in noted that China produces an abundant pipeline of engineering graduates and that CXMT’s compensation packages are competitive across industries, enabling rapid scaling. He added bluntly that Samsung and SK Hynix “cannot be said to have sufficient R&D personnel relative to their revenue and global standing.”
The uncomfortable truth is that Korea’s memory-chip advantage rests on a headcount gap that is narrowing fast. SK Hynix and Samsung collectively employ roughly 25,000 to 30,000 researchers across their memory divisions. Together they still outnumber CXMT nearly four to one. But the dynamics matter more than the absolute gap: SK Hynix added 547 researchers last year. CXMT added 2,836. The slope of the curve favors the challenger.
Korea faces additional headwinds beyond the hiring imbalance. Its semiconductor workforce is aging. The country’s birth rate has fallen to historic lows, and the pool of young engineers willing to enter the hypercompetitive fab environment is contracting. Meanwhile, China is actively recruiting Korean and Taiwanese memory engineers through lucrative packages and residency pathways — a reverse flow of talent that did not exist a decade ago.
There is a second-order risk as well. China’s push toward EDA tool localization and domestic memory production is not just about catching up — it is about building an alternative supply chain that does not depend on Korean fabs. If CXMT achieves self-sufficiency in both design tools and fabrication, Korean manufacturers lose not only a share of the DRAM market but also a strategic bargaining position in the broader chip ecosystem.
The geopolitical dimension cannot be ignored either. CXMT’s rise coincides with increasing U.S. pressure on South Korea to align with semiconductor export restrictions targeting China. Seoul finds itself caught between maintaining economic ties with Beijing and preserving its security partnership with Washington. If CXMT continues gaining share, Korea’s leverage in this balancing act diminishes further.
Second-Order Consequences for the Global Memory Market
Beyond the direct headcount competition, several structural shifts are underway. First, the DRAM pricing model — long dominated by the triopoly of SK Hynix, Samsung, and Micron — is beginning to fragment. CXMT’s willingness to offer competitive pricing on LPDDR6 and HBM3E introduces margin pressure that the incumbents have not faced in over a decade. Even if CXMT’s yields lag behind SK Hynix’s by 10 to 15 percent, which they likely do at current volumes, the mere existence of a credible second source changes buyer behavior. Procurement teams negotiate harder; contracts include contingency clauses; and switching costs decline.
Second, the HBM market — currently the fastest-growing segment in semiconductors — is about to become more complex. SK Hynix dominates HBM3E shipments to NVIDIA, and Samsung is aggressively closing the gap. CXMT’s entry, even at small scale, signals that a third supplier is viable. For AI chipmakers, this is a double-edged sword: more supply diversification reduces dependency risk, but it also means the premium margins SK Hynix commands today face downward pressure sooner than expected.
Third, and perhaps most consequential, is the implication for the rest of China’s semiconductor ecosystem. CXMT is not operating in isolation. Its growth creates demand for domestic foundry capacity, packaging services, and equipment — sectors that have long been starved of investment relative to design. Huawei’s Semiconductor Manufacturing International Corporation (SMIC), packaging specialist ChangXin Microelectronics, and equipment makers like AMEC all benefit from the demand signal CXMT sends to Chinese investors and policymakers. The effect is a compounding flywheel: each new capability makes CXMT more self-reliant, which justifies further investment, which builds additional capability.
What Comes Next
CXMT’s trajectory suggests three likely developments over the next 18 to 24 months.
First, the company will continue to close the R&D headcount gap with SK Hynix, likely reaching parity within two to three years if current hiring rates hold. At the present pace, CXMT would need approximately 2,000 to 2,500 additional researchers per year to achieve numerical equality. That is aggressive but not unrealistic given Beijing’s continued funding commitment and the availability of qualified domestic graduates.
Second, HBM production volume will scale beyond the current small-batch phase, putting CXMT in direct competition with SK Hynix for NVIDIA and other AI-chip customers. Initial volumes are modest — likely measured in thousands of units per month rather than the hundreds of thousands SK Hynix ships — but scale in HBM follows the same learning-curve dynamics as conventional DRAM. Every generation of improved yield narrows the cost gap.
Third, the government’s industrial policy will deepen — expect further subsidies, talent incentives, and procurement mandates that make CXMT’s growth even more insulated from market cycles. Beijing has demonstrated a willingness to absorb short-term losses for long-term strategic gains. CXMT is a vehicle for that strategy, and vehicles like it do not receive defunding.
For Korean fabs, the response cannot be reactive. It requires accelerating hiring, expanding graduate recruitment pipelines, and investing in next-generation memory architectures that CXMT cannot easily replicate — such as HBM4, CXL-enabled memory, and photonic interconnects. Korea must also confront its demographic reality: competing on headcount alone is a losing proposition. The advantage lies in depth of expertise, not breadth of bodies.
The window is still open, but it is closing faster than the headlines suggest.
China did not win the memory-chip war by outspending Korea. It won by outlasting it — and CXMT’s 60 percent R&D expansion is the latest proof that the strategy is working.