France's Debt Relief Debate Could Reshape Global Capitalism
Jean-Luc Mélenchon's 'debt cancellation' platform in France signals a growing ideological challenge to sovereign debt norms. If creditor nations begin treating private wealth as forfeitable in crises, the consequences ripple far beyond Europe.
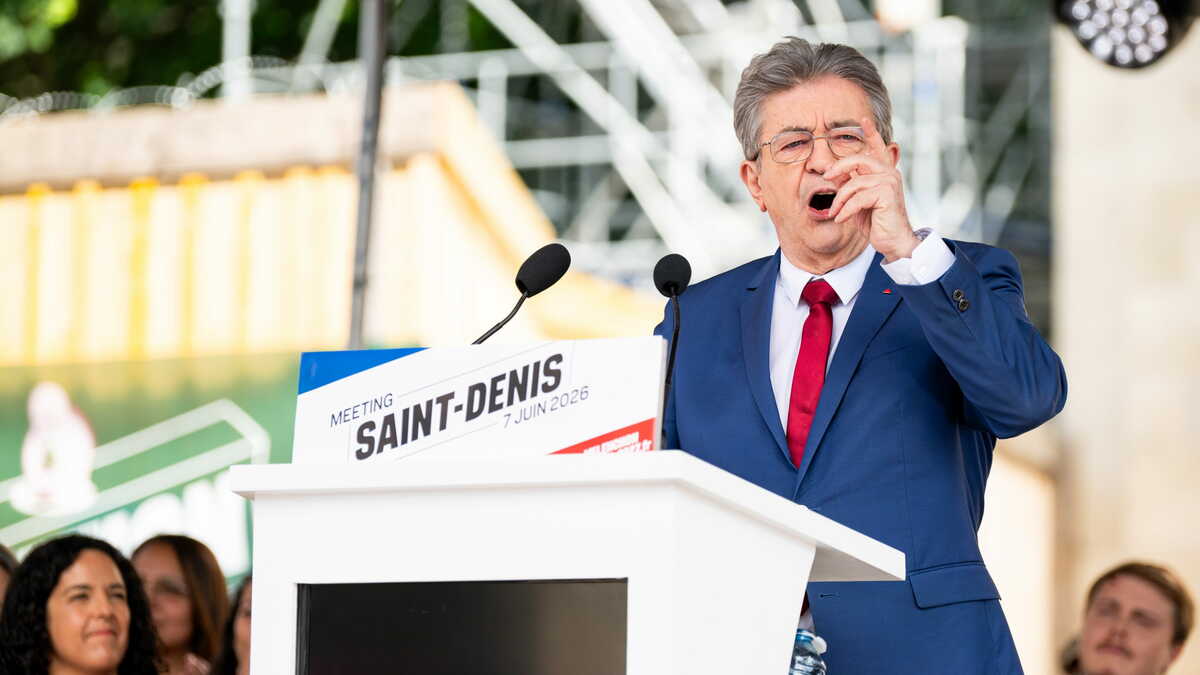
The Idea That Changes Everything
Jean-Luc Mélenchon is not running on a platform of modest fiscal tweaks. The leader of La France Insoumise, or “Unyielding France,” has placed debt cancellation at the center of his presidential bid — a move that would directly challenge the bedrock assumption of modern capitalism: that private property is inviolable.
This is not a fringe economic proposal dressed in radical language. It is a genuine ideological question about what happens when the state faces an existential crisis. If a government can cancel sovereign debt, can it also reach into the pockets of its own citizens and seize what they own to pay for survival? The answer, as France is quietly debating, may rewrite the social contract in ways global investors are only beginning to grasp.
The Legal Precedent Is Already There
Mélenchon’s argument rests on a legal foundation that exists in multiple constitutions and international instruments — and it cuts both ways. Article 17 of the Universal Declaration of Human Rights recognizes the right to own property. But it does not declare that right absolute.
Japan’s Constitution is instructive here. Article 29, Paragraph 1 guarantees that property rights shall not be violated. Paragraph 3 immediately qualifies it: private property may be taken for public use with just compensation. The existence of the exception is the story. A state that can redefine “just compensation” during a crisis has, in effect, created a backdoor to confiscation.
The logic is stark: property rights exist because the state enforces them. When the state faces ruin, it can suspend its own enforcement mechanism. The property was never truly secure — it was always contingent on political will.
This is not abstract theory. It echoes through history. Emergency decrees canceling debts date back to ancient Mesopotamia. Modern precedents include Argentina’s 2001 default, which wiped out roughly $100 billion in sovereign obligations, and Greece’s 2012 debt restructuring that imposed a 53 percent nominal loss on private bondholders. Each time, the market reacted with shock and horror. Each time, the alternative — total state collapse — proved more terrifying.
Why France Matters Now
France carries particular weight in this debate because it sits at the fault line between fiscal orthodoxy and political upheaval. The country’s public debt exceeds 110 percent of GDP. Interest payments consume an increasing share of the budget. The political center has been hollowed out. And a candidate like Mélenchon, who frames debt cancellation as moral restitution rather than economic recklessness, is gaining credible traction.
The European Central Bank has long operated on the assumption that core eurozone members would never permit their governments to default. That assumption is now being tested from the left, not from the populist fringes of Southern Europe but from a country whose constitutional tradition is deeply embedded in the postwar order. If France entertaining debt cancellation as a serious policy option, the credibility of every bond held by foreign investors in Paris becomes conditional on electoral outcomes.
Who Wins. Who Loses.
The winners from a credible debt cancellation framework are straightforward: solvent households and small businesses caught in a high-debt economy, younger generations burdened by inherited fiscal obligations, and governments seeking fiscal space without raising taxes. The losers are equally clear: bondholders, pension funds, insurance companies, and any investor who priced French debt as risk-free. Cross-border holders — including Japanese institutional investors and German banks with French exposures — face direct losses if restructuring imposes haircuts on private creditors.
But the deeper loser is the concept of the rule of law itself, at least as investors understand it. Property rights are not a natural force. They are a political guarantee. When that guarantee becomes negotiable, every sovereign bond in the world carries a new variable: the willingness of a electorate to confiscate wealth in a crisis.
The Ripple Beyond Europe
Japan’s own debt dynamics make this debate uncomfortably relevant. Japan’s public debt stands at over 250 percent of GDP — the highest among advanced economies. Its creditors are overwhelmingly domestic: the Bank of Japan, Japanese banks, and Japanese pension funds. The risk of a Mélenchon-style scenario in Japan is lower, precisely because the debt is held at home. But the precedent matters. If France normalizes the idea that democracies can cancel debts and seize assets, the psychological barrier protecting Japanese government bonds weakens — not because Japanese investors would face French-style confiscation, but because the global narrative around sovereign risk shifts.
Emerging markets with large external debts denominated in foreign currencies face a different calculation. A wave of debt cancellation in Europe could encourage parallel demands elsewhere — in Latin America, in Africa, in Asia — transforming a regional political debate into a global restructuring impulse.
What Happens Next
Mélenchon is not guaranteed victory. French presidential elections have proven unpredictable. But the fact that debt cancellation is now a mainstream campaign issue — discussed in serious economic terms rather than dismissed as fantasy — signals a realignment. The next decade of European politics will likely see more candidates testing the boundary between fiscal responsibility and fiscal revolt.
Investors should price in three scenarios: first, a France where Mélenchon or a similar candidate wins and attempts restructuring, creating immediate market chaos and legal battles with the European Court of Justice; second, a France where the idea survives politically even if the policy does not, keeping a persistent risk premium on French bonds; and third, a Europe where other nations adopt preemptive restructuring strategies to avoid the worst outcomes, gradually normalizing haircuts on private creditors.
None of these scenarios is guaranteed. All of them are possible. And the common thread is that the postwar consensus — that sovereign debt in core Europe was effectively unrisks — is no longer operating beneath the surface of political discourse. It is being argued about openly, in presidential campaigns, in legal journals, and in the kind of economic magazine that asked the question Mélenchon’s platform makes impossible to ignore: what happens to capitalism when the state decides that private property is no longer sacrosanct?
The answer will determine not just France’s future, but the pricing of debt across the world.