France's fiscal trap: when protesters and bond markets both win
France is caught between streets demanding spending and markets demanding restraint. The result is a fiscal trap that threatens not just the country but the entire eurozone.
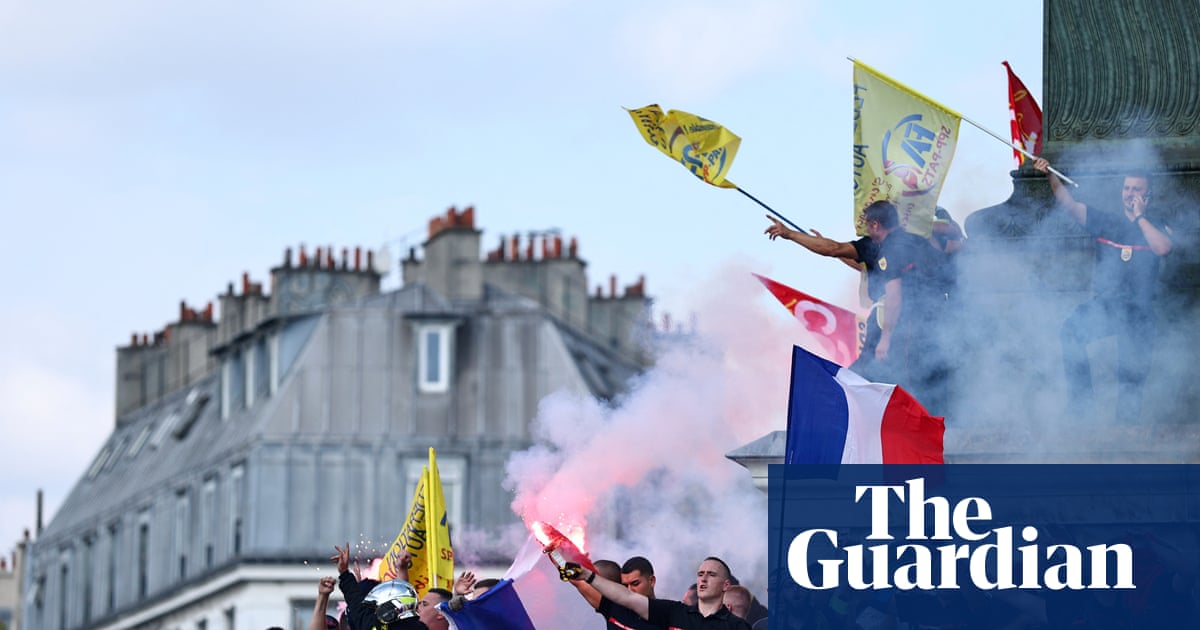
The Street and the Bond Vigilantes
France is learning that democracy and markets do not always shake hands.
Students and workers have blockaded roads again. They demand spending — on schools, on nurses, on judges. The same demands that filled the streets eight years ago with yellow vests have returned, sharper and more organised.
At the same time, bond markets are doing what bond markets do: they are pricing in the risk that France cannot pay its way out of this.
The yield on 10-year French bonds hit nearly 5% last week — the highest since July 2002. Japanese investors, traditionally among France’s most reliable buyers, have been selling. They found better returns at home. That left French borrowing costs exposed and alone.
This is not a routine downturn. It is a structural trap, and it points to something deeper about European politics.
The Numbers Are Bad, But Not the Whole Story
France’s debt-to-GDP ratio stood at 115.6% in 2025. The budget deficit was 5.1%. For comparison, the UK sat at 94.3% debt and 4.3% deficit. Britain’s chancellor, John Healey, is projecting deficit reduction. France’s finance minister, Roland Lescure, has promised to follow — after a rise to 5.4% this year — but has offered no details on how.
The French economy is not without strengths. Electricity prices are lower than most neighbours. Infrastructure is solid. Schools are better funded than the OECD average.
None of that matters much when the pension reform — raising the retirement age from 62 to 64 — stalled at 62 and nine months. The savings never arrived. Growth remains stuck. And the political class offers no coherent answer.
Everyone Wants Something Different
The real puzzle is not the numbers. It is the politics.
Marine Le Pen, frontrunner for next year’s presidential election, wants to lower the pension age back to 62. She also wants a debt brake via referendum. She wants more nurses, teachers, police officers and judges. She has become, in her own way, an improbable fiscal hawk — a position that makes no sense to anyone who remembers the National Rally’s populist spending past.
Jean-Luc Mélenchon, leader of La France Insoumise, wants the opposite: more spending, more public investment, no austerity. His runoff against Le Pen is now the scenario that terrifies markets most.
Antonio Fatas, an economics professor at Insead, put it plainly: “I am panicking.” He added that too many political parties seem to want crisis, believing it will improve their votes.
That is the trap. No major party can deliver the spending protesters demand and the fiscal discipline markets require. Every coalition that might form next year contains that contradiction at its core.
Too Big to Save
The most arresting phrase to emerge from this debate comes from Paul Krugman. France, he said, may have crossed the line from too big to fail to too big to save.
A bailout would be enormously expensive. The European Central Bank could mount a rescue, but France would likely demand unconditional support — and the ECB’s rules require conditions. The math does not work either way.
Erik Britton, director of Fathom Consulting, estimates a Le Pen presidency carries roughly a 20% risk of Frexit. A Mélenchon presidency carries an even higher risk, though one that markets find harder to price because it comes from the left rather than the right.
“Where France goes, the euro area as a whole tends to follow,” Britton said. If France tests the euro again, bond yields could spike across the bloc — except in Germany, which would benefit from a flight to safety.
That is the spillover risk that keeps eurozone finance ministers and ECB officials awake. Several have reportedly made representations to the French government, urging it to produce a budget formula that can command a parliamentary majority and satisfy leading lenders.
Without a budget, France faces itself. And if traders boycott French bonds without a premium, default becomes a real possibility.
Who Wins, Who Loses
Business investment is already paying the price. A survey by Medef, France’s largest employer federation, found 82% of firms pessimistic about the next government’s economic policy. Two-thirds said their business would become vulnerable or go bankrupt if policy remained deadlocked for five years.
Workers and students on the streets lose because their demands are unaffordable under current market conditions. Markets lose because France’s instability raises the cost of borrowing for everyone in the eurozone. The ECB loses credibility because it cannot help without breaking its own rules. Politicians lose because no one can deliver a convincing answer.
The one possible winner is the bond vigilante — the trader who tests each market for weakness before launching a full attack. Albert Edwards of Société Générale noted that France is currently in the crosshairs, but the focus may shift next month to Japan, the UK or the US. These traders do not pick sides. They find the weakest link.
What Comes Next
France will have to make painful adjustments to restore fiscal sanity. Italy, Spain and Greece did so a decade ago, emerging stronger on the other side. The question is whether France can endure the political pain without fracturing the euro.
Emmanuel Macron contemplates his exit in 2027. He leaves behind a country that is too large to let fall and too divided to fix itself.
The streets will return if spending cuts come. They will return if nothing changes. The bond vigilantes will keep testing. And Europe will watch to see whether the second-largest economy in the eurozone can navigate a path that no politician seems able to draw.
That is the real story here. Not just France’s debt. France’s inability to answer the question that every indebted democracy now faces: how do you fund the promises you have made when the markets are no longer willing to lend?