Japan's 300mm SiC Breakthrough Could Reshape EV Chip Supply Chains
Resonac's announcement of a 300mm silicon carbide substrate is more than a materials milestone. It could shift who controls next-generation power-semiconductor manufacturing — and why Tesla, BMW, and the US equipment industry should pay attention.
The quiet Japanese move that could upend power-semiconductor economics
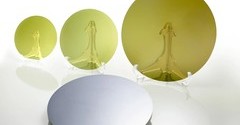
Resonac, formerly Hitachi Chemical, announced on September 15 that it had successfully grown and processed a 300mm (12-inch) silicon carbide single-crystal substrate — a first at that scale and one of the largest diameters currently in development worldwide.
The announcement itself is measured. Resonac called it a “critical technical milestone” and said it would continue supplying “high-performance, high-reliability SiC materials.” No fanfare about mass production timelines. No mention of customers.
But the implications are anything but incremental.
Why 300mm SiC matters more than the diameter
Silicon carbide is already the material of choice for high-voltage, high-temperature power electronics. EVs use it in traction inverters. Charging stations need it. Industrial motor drives can’t easily replace it. The core advantage over conventional silicon is stark: SiC switches with far lower conduction loss and less heat generation, directly translating into longer driving range and smaller thermal management systems.
Yet SiC has always carried a geometry penalty. Until now, the dominant substrate size for commercial SiC wafers has been 150mm (6-inch) and, more recently, 200mm (8-inch). Moving to 300mm isn’t simply about fitting more dies on a wafer. SiC crystal growth is brutally slow — growth rates are measured in millimeters per hour, not the rapid vapor deposition used for silicon — and the material is extremely hard and brittle. A 300mm boule requires dramatically more time, energy, and precise thermal control than a 200mm one, and the defect density must stay low across a much wider area.
Getting a 300mm substrate out of the lab and into a reproducible process is a materials-science step that the entire industry has been working toward for years.
The economics that change at 300mm
If Resonac can actually deliver 300mm SiC substrates at viable defect levels, the unit economics shift meaningfully. A 300mm wafer holds roughly 2.25 times the die count of a 150mm wafer and about 1.5 times that of a 200mm wafer. Even accounting for yield losses that tend to be worse on larger substrates, the cost per die drops sharply — and in a market where SiC devices already run at a premium over silicon IGBTs, every percentage point of cost reduction opens new applications.
Lower-cost SiC means manufacturers can push the technology into segments that were previously marginal: on-board chargers, DC-DC converters, even 48-volt mild-hybrid architectures that have so far stuck with silicon.
Who loses — and why it matters for the US equipment niche
The SiC substrate business is unusually concentrated. American supplier Wolfspeed has historically dominated large-diameter SiC substrate supply, particularly at the 150mm and 200mm levels. European players like III-V Ltd (now part of Onyx Industries) and Germany’s IQE also hold significant positions. Japanese firms including Sumitomo Electric and Showa Denko (now Shin-Etsu’s compound-semiconductor unit) have their own substrate lines.
Resonac’s entry at 300mm is not an immediate competitive threat to any of them — the source material doesn’t claim volume production, and no fab has signed on yet. But it signals that Japan is preparing to compete for the next round of SiC substrate demand, and it arrives at a moment when Western equipment suppliers have built substantial revenue streams servicing SiC crystal-growth furnaces and substrate-processing tools for existing 200mm lines.
A transition to 300mm SiC will require different tooling, different chamber designs, and potentially entirely new process workflows. That is both a risk and an opportunity for the equipment side. Equipment vendors that only service current-generation 200mm lines may find their installed base plateauing faster than expected.
The NEDO connection — and what it reveals about strategy
The announcement makes clear that Resonac drew on results from Japan’s New Energy and Industrial Technology Development Organization (NEDO) Green Innovation Fund, specifically a program titled “Development of SiC wafer technology for next-generation green power semiconductors.” This is not a corporate R&D exercise in isolation. It is government-backed industrial policy aimed squarely at securing Japanese leadership in a strategic materials segment.
That context matters because it frames the 300mm breakthrough not as a singular technical achievement but as part of a coordinated effort to reduce Japan’s reliance on imported power-semiconductor substrates and to position Japanese manufacturers as suppliers to the very EV and industrial players that currently source from American and European vendors.
What this means for the automakers
Tesla and BMW have been public about their interest in SiC. Tesla’s Model 3 and Model Y traction inverters use SiC MOSFETs from companies like Wolfspeed and STMicroelectronics. BMW’s Neue Klasse platform, announced for launch in 2025, is built around next-gen SiC power modules. Both companies care deeply about reducing the cost per kilowatt of onboard power electronics — an area where 300mm substrate economics would help directly.
For automakers, the upside is straightforward: cheaper SiC devices accelerate the case for full-SiC inverter designs across more vehicle models, not just premium trims. The risk is supply concentration. If Resonac, Sumitomo, and Showa Denko all scale 300mm simultaneously, automakers gain leverage. If only one or two succeed, the market remains supplier-tight and prices stay elevated.
What we don’t yet know
The Resonac announcement does not disclose whether the 300mm substrate is defect-free enough for epi-wafer growth, whether it has been tested in actual power-device runs, or what timeline exists for volume production. It also does not name any customers. In SiC, the jump from a successful crystal growth to a commercially viable substrate has repeatedly proven harder than anyone expects — crystal inclusions, micropipe density, and bow-and-warp issues tend to multiply as diameter increases.
Until those data points exist, this remains a promising materials milestone rather than a market-moving event.
The bottom line
Japan is positioning itself to compete at the top of the SiC substrate hierarchy at a time when the EV power-electronics market is still expanding rapidly and still dependent on a small number of Western suppliers. The 300mm breakthrough is not a finished product announcement. But the direction is unmistakable: the next generation of SiC supply chains will be shaped by whoever can deliver larger-diameter substrates reliably, and Japan is now making a credible claim in that race.