Korea's Semicon-Growth Trap: A Former Central Banker's Warning
Former central bank governor Lee Chang-yong argues that Seoul's fixation on public-firm relocations and chip-driven GDP masks a deeper structural crisis. The real question is whether export-dependent East Asia can survive the supercycle's tail.
The Illusion of the Silver Bullet
When you stand at a certain altitude, the economic data of an export-driven Asian economy looks beautiful. The numbers climb. The global market for memory chips is roaring. The central bank keeps interest rates low to feed the boom. But if you descend to street level — or rather, if you listen to the person who once ran the country’s monetary machinery — you hear a different story.
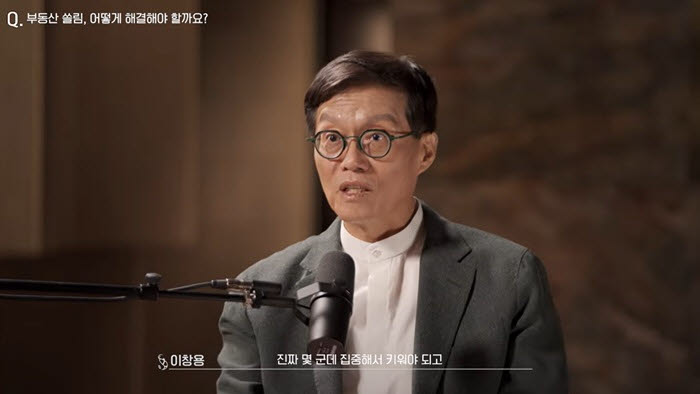
Lee Chang-yong, the former governor of the Bank of Korea, recently appeared on a YouTube program and delivered a critique that cuts through most of the optimistic rhetoric surrounding Seoul’s latest policy push: a second round of public-firm relocations from the capital to the provinces. His conclusion? If you scatter fifteen companies across fifteen districts, nothing changes. The concentration remains. The inequality deepens. And the illusion of structural reform persists.
This is not just a local dispute about bureaucratic zoning. It is a diagnostic moment for the broader East Asian model — an model built on the premise that export engines, even when fueled by semiconductor cycles, can substitute for genuine regional rebalancing.
The Scattered Relocation Trap
The idea behind moving public corporations out of Seoul is not new. For years, successive Korean governments have spent billions building innovation cities in the provinces, assuming that physical presence would catalyze development. The assumption was mechanical: companies move, jobs follow, infrastructure is built, young people settle, the region thrives.
What Lee observed is that the strategy failed precisely because it was designed to spread rather than concentrate. When a corporation relocates to a satellite city but retains its decision-making nexus in Seoul, employees commute. Hospitals, cultural facilities, and the ecosystems that attract talent remain anchored in the capital. The new location becomes a dormitory town, not a competitor.
Lee’s proposal was blunt: pick two or three sites and invest in them aggressively. Build world-class hospitals. Construct cultural infrastructure. Create amenities that would make a potential resident choose the new city over Seoul — not just a desk and a parking lot. Concentration, not diffusion, would be the path to a real counterweight.
The political obstacle is enormous. Every lawmaker wants their district to benefit. No one wants to be the one to tell a constituent that their city lost the lottery. This is the classic collective-action problem that plagues structural reform everywhere, and it is why most relocation schemes produce the exact outcome Lee warned against: a few hollow achievements and a great deal of wasted capital.
The Supermarket Effect in Housing
Lee turned the same analytical lens on South Korea’s housing market, where what should be a basic shelter issue has morphed into something resembling a national lottery. The pre-sale price cap system, introduced with the progressive intention of protecting first-time buyers from speculation, has become, in his words, a “national lottery ticket.” Anyone with a savings account can apply. Winning feels like a windfall. Losing generates social resentment.
This dynamic is peculiarly Korean but structurally familiar. When housing is treated as both consumption and investment, and supply is constrained while demand is managed through administrative pricing rather than market mechanisms, you get a zero-sum game. The winners celebrate. The losers blame the system. Everyone expects the next draw to be their turn.
The policy feedback loop is even more damaging. Government lending programs designed to help young couples and low-income families ended up inflating the very prices they were meant to mitigate. Roughly half of all bank loans in Korea are now tied to policy financing, meaning the state is simultaneously subsidizing demand and absorbing risk. The result is a self-reinforcing cycle: subsidies boost purchasing power, prices rise, new subsidies are needed to maintain affordability, and the fiscal exposure grows.
The Semiconductor Mirage
Here we arrive at the question that matters most for the region: Can the current semiconductor supercycle sustain East Asian growth models indefinitely?
The evidence suggests no. The chip market operates in brutal cycles. Demand surges during technology transitions — artificial intelligence, data-center buildouts, automotive electrification — and then plateaus or contracts when those waves normalize. Korea’s economy, heavily weighted toward memory semiconductor exports, is exquisitely sensitive to these swings. When the cycle turns, GDP growth does not merely slow; it distorts, because the statistical boost from high-value chip exports makes underlying weakness harder to see.
Lee’s warning carries this implication without stating it explicitly: a growth figure driven by a single commodity cluster is not structural strength. It is a temporary alignment of global demand with national export capacity. When that alignment shifts, the structural imbalances remain — the Seoul concentration, the regional inequality, the housing distortions, the policy dependencies — and now they sit atop a lower growth baseline.
This is not unique to Korea. Japan experienced a version of this in the 1980s, when electronics and precision manufacturing fueled expansion that masked demographic and regional decay. Taiwan faces similar dynamics, where semiconductor dominance elevates GDP metrics while agricultural communities and secondary cities empty out. The pattern is recognizable: export-engine growth creates the illusion of comprehensive development while concentrating opportunity in narrow corridors.
The Tax Reform Question
Lee offered a prescription for the tax side of the housing problem: raise property holding taxes, lower transaction taxes. The logic is straightforward. Currently, selling a property triggers a significant tax hit, which discourages movement and locks up inventory. Holding a property, by contrast, is cheap. The system rewards stagnation. Flip the incentives, and you encourage supply — older homeowners in prime areas sell, younger buyers move in, and the flow of housing stock improves.
But Lee acknowledged that this reform requires cross-party agreement, which is unlikely under normal political conditions. Tax changes are electorally toxic. No party wants to be remembered as the one that raised property taxes without delivering visible relief. His recommendation — negotiate a binding framework that survives electoral turnover — is institutionally sound but politically naive in a system where policy whiplash is the norm.
The Regional Diagnosis
What makes Lee’s commentary significant is that it treats Korea’s problems as interconnected rather than siloed. The relocation failure, the housing lottery, the policy-financing trap, the semiconductor dependency — these are not separate issues. They are symptoms of a single condition: an economy that has optimized for growth metrics while neglecting structural resilience.
The supercycle is masking the diagnosis. As long as chip exports are strong, as long as GDP figures are impressive, as long as the international narrative celebrates Korea’s tech leadership, there is little political incentive to confront the underlying architecture. Lee’s contribution is to insist that the architecture matters precisely when the supercycle ends.
For readers outside the region, the lesson extends beyond Korea. Any economy built on export concentration, administrative pricing, and cyclical commodity booms shares this vulnerability. The difference is that Korea has a former central bank governor willing to say it publicly.
The harder question is whether anyone in power is listening.