How Middle East Chaos Could Upend Japan's Monetary Strategy
Houthi attacks on Saudi infrastructure are reigniting Red Sea risk — a threat that travels directly to Tokyo's yield-curve management and Japan's energy-dependent economy.
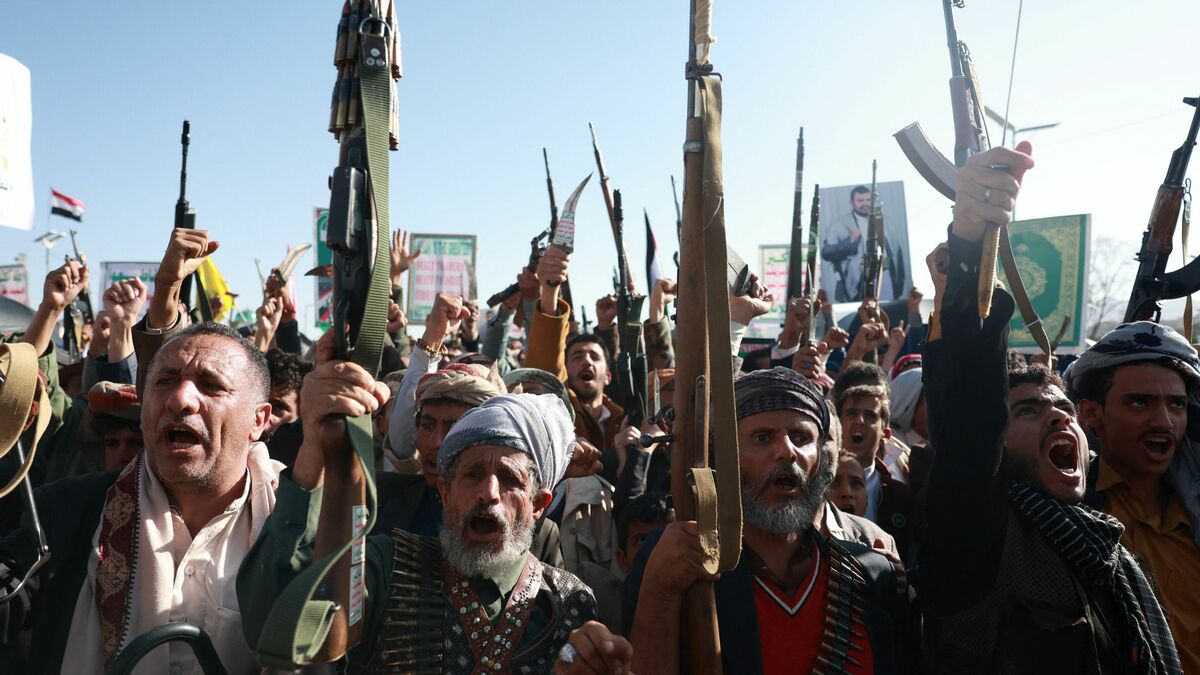
The Attack That Should Worry Tokyo
On October 10, 2026, missiles struck Riyadh’s King Khalid International Airport, killing at least 13 people and wounding over 300. In the days that followed, Houthi forces targeted another airport in the southwest, the headquarters of state oil company Saudi Aramco, and the fire-lit port of Yanbu — the western terminus of Saudi Arabia’s East-West Pipeline, the critical alternative export route that bypasses the Strait of Hormuz.
Saudi Arabia is not just any regional actor. It is the Middle East’s second-largest economy after Turkey, with a GDP of roughly $1.3 trillion at 158 yen per dollar. Crown Prince Mohammed bin Salman has staked his political legacy on Vision 2030, a multi-year effort to transform the kingdom away from crude dependency. Hosting the 2034 FIFA World Cup was supposed to be one of its capstones. The Houthi campaign — backed by Iran, which is now awkwardly positioning itself as a mediator — is not just a regional security problem. It is a direct threat to the trade routes that supply the energy Japan cannot produce itself.
Who Wins, Who Loses
Iran gains the most ambiguous advantage. By allowing its proxy to escalate while simultaneously offering dialogue, Tehran keeps pressure on Saudi Arabia without fully committing to a wider war. If the Houthis can sustain attacks on Saudi infrastructure, they degrade MBS’s domestic credibility — the very foundation of his reform agenda. The crown prince’s vision depends on stability attracting foreign investment and hosting global events. Every missile that lands near an airport or a pipeline endpoint sends a different message to international investors.
Saudi Arabia loses on two fronts. First, its sovereignty is visibly challenged inside its own capital. Second, and more consequential, the Red Sea route that replaces the Hormuz chokepoint is itself coming under fire. Yanbu is not a symbolic target. It is where roughly 20 percent of Saudi crude once flowed westward before Houthi attacks on shipping began redirecting traffic back through the Persian Gulf. Any further degradation of that pipeline endpoint narrows Saudi export options and increases reliance on a single, vulnerable corridor.
The Houthis, for their part, have proven they can strike deep into Saudi territory with limited cost. Their attacks are cheap relative to the defensive spending they force Riyadh to absorb. But they also risk overplaying their hand — drawing in a broader confrontation that could endanger their own position in Yemen.
The Japan Link Most Western Outlets Miss
Here is what English-language coverage of this escalation rarely connects: Japan imports approximately 88 percent of its energy from the Middle East, and roughly 90 percent of that crude transits the Strait of Hormuz or the Red Sea. When Houthi attacks threaten the East-West Pipeline at Yanbu, they are not just hitting a Saudi facility. They are compressing the alternative route that global traders have relied on since Red Sea shipping became dangerous in 2023.
Oil price spikes from Middle East escalation do not stay in the Middle East. They move instantly through global benchmarks — Brent, Dubai Crude, Oman — and Japan pays for its imports on those same references. A disruption that pushes Brent above $100 a barrel, let alone $110 or $120, would reawaken imported inflation in a country where core CPI has only recently been creeping toward the Bank of Japan’s 2 percent target.
And that is where the yield-curve strategy becomes fragile.
The BOJ’s Tightrope
The Bank of Japan ended its negative-rate regime in March 2024 and has since been carefully unwinding yield-curve control, allowing the 10-year government bond yield to drift upward. The strategy is deliberate but extraordinarily sensitive to external shocks. A sudden oil-driven inflation spike would force the BOJ into an impossible position: let rates rise faster than planned to contain imported price pressures, or hold course and risk the yen’s depreciation accelerating into something disruptive.
Japan’s current account surplus — historically a buffer against yen weakness — compresses rapidly when oil import bills surge. The BOJ watched this dynamic closely in 2022 and 2023, when energy prices after the Ukraine invasion pushed the yen below 150 to the dollar and forced repeated intervention. A fresh Middle East shock would replay that scenario, but with less policy flexibility than existed then. The BOJ’s balance sheet remains enormous, but the room to intervene in currency markets without conflicting with its own yield-curve objectives is narrow.
What Happens Next
Iran’s offer of dialogue is theatrical but not meaningless. It signals that Tehran wants to preserve the Houthis as a leverage tool while avoiding a full-scale war that could close the Strait of Hormuz entirely — a scenario that would devastate not just Saudi exports but global oil supplies, since roughly 20 million barrels per day flow through that strait. If the Houthis escalate beyond infrastructure targeting toward actual shipping interdiction in the Red Sea, the economic consequences multiply quickly.
For Japan, the question is whether the BOJ can absorb another energy shock without derailing its gradual normalization path. The answer depends on how far oil prices climb and how long the uncertainty persists. Either way, the next major Houthi strike on Saudi soil will reverberate in Tokyo’s bond market within hours.
The Middle East is not distant from Japan. It is priced into every barrel, and every barrel is priced into the BOJ’s calculus.