South Korea's Back-to-Back Rate Hike Is a Wake-Up Call for Asian Markets
The Bank of Korea's second consecutive rate hike to 3% breaks a three-year pattern and signals that inflation pressures are deeper than expected. The move reshapes the outlook for the won, regional currencies, and Asian supply chains.
A Move Three Years in the Making
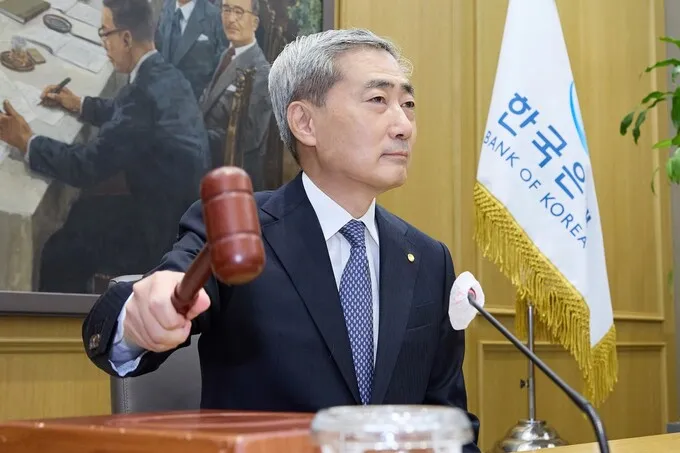
The Bank of Korea raised its base rate to 3.00% on August 27, marking the second consecutive monthly increase — a pace of tightening rarely seen outside of crisis moments. The last time the central bank delivered back-to-back hikes was October and November 2022, during the worst of the post-pandemic inflation wave. Three years and nine months later, history is repeating itself, and this time the reasons may be more structurally entrenched.
The decision came with a 6-to-1 vote in favor among the nine-member Monetary Policy Board. That margin is notable. One dissenter might signal internal doubt; six votes suggest the committee sees a clear and present danger that demands action now, not next year.
The Data Behind the Decision
What surprised markets was not just the hike itself but the speed with which underlying conditions hardened. The second-quarter GDP growth figure — 0.6% quarter-on-quarter — smashed through the Bank of Korea’s own forecast of 0.2%. The divergence was stark. On the surface, strong growth should be welcome. But in this context, it meant the economy was running hot enough to fuel demand-side inflation without the central bank needing to coax a recovery from the abyss.
The real GDI — gross domestic income adjusted for purchasing power — told an even more alarming story. It surged 3.6% quarter-on-quarter and 15.6% year-on-year. That is not a modest uptick. It represents a significant expansion in real household and corporate income, and with income comes spending. When spending outpaces supply, prices rise. The Bank of Korea could no longer pretend inflation was a temporary headline driven by energy or food.
Semiconductor exports provided much of the growth engine. South Korea’s memory-chip sector has been riding a cyclical upswing, and the numbers reflected it. But export strength also means a stronger won, which feeds back into the currency equation in ways that matter for the broader region.
The Debt Problem No One Ignores Anymore
Perhaps the most consequential data point arrived quietly: South Korean household debt crossed the 2,000 trillion won threshold for the first time in June. That is roughly $1.4 trillion USD, a figure that dwarfs the country’s annual fiscal surplus and underscores how deeply leveraged families are heading into a tightening cycle.
Household debt has long been a sleeping risk in South Korea. The government tolerated it because cheap credit fueled consumption and kept growth estimates plausible. Now that the Bank of Korea is raising rates twice in a row, the debt service burden on millions of borrowers is accelerating. Mortgage holders with variable-rate loans are feeling it immediately. The Seoul housing market, already showing signs of overheating in certain districts, is now colliding with higher borrowing costs — a combination that could either cool prices sharply or push desperate sellers into distress.
What Happens Next
Financial markets are pricing in further rate increases. The August hike was not seen as a one-off signal; it was the opening move of what many analysts expect to be a series of gradual adjustments through the remainder of 2026. The Bank of Korea upgraded its full-year growth forecast to 3.3% from 2.6%, which gives it some room to breathe — strong growth buys policy flexibility. But that same upgrade means the central bank is acknowledging that the economy can absorb tighter conditions, removing the usual excuse for delay.
For the won, the immediate effect is appreciation pressure. A higher rate differential against Japan and other regional central banks makes Korean assets more attractive, which supports the currency but complicates the export story that just made the strong GDP number in the first place. It is a feedback loop: export strength strengthens the won, which dampens future export competitiveness, which the central bank must weigh against inflation.
For emerging-market investors, the ripple effects travel further. South Korea is both a major consumer of intermediate goods and a supplier of semiconductors, display panels, and batteries to the rest of Asia. A tightening cycle here reduces domestic demand for inputs from Taiwan, Japan, and China. It also signals that the era of easy money — which fueled speculative capital flows across EM debt and equity markets — is receding faster than some portfolios were positioned for.
Who Wins, Who Loses
The Bank of Korea wins credibility. By acting decisively rather than waiting for inflation to become entrenched, it avoids the mistake that plagued many central banks in 2021 and 2022. The export-oriented corporations that drove the Q2 growth beat win too — at least in the near term, because their revenue is measured in dollars and euros, not won.
Variable-rate borrowers lose. Homeowners with adjustable mortgages, consumers carrying credit-card debt, and companies relying on short-term financing all face higher costs immediately. The 2,000-trillion-won household debt overhang means this is not a marginal group — it is a substantial share of the population.
Regional central banks watching closely may find their own inflation battles made harder. If the won strengthens significantly, it puts competitive pressure on the yen, the yuan, and other Asian currencies. Each of those banks faces its own domestic constraints, and a stronger regional benchmark currency means less room to ease without triggering capital outflows.
The lesson from August 27 is that South Korea’s economic miracle has a debt ceiling, and the central bank is finally writing against it. The back-to-back hike was not a panic move. It was a warning shot — and the rest of Asia should be listening.