Ubtech's IPO Reveals China's Plan to Weaponize Capital Markets
Ubtech's 629% debut on Shanghai's ChiNext isn't just a stock story—it's the latest move in Beijing's campaign to fuse capital markets with geopolitical strategy. The question is whether that strategy can survive the US ban.
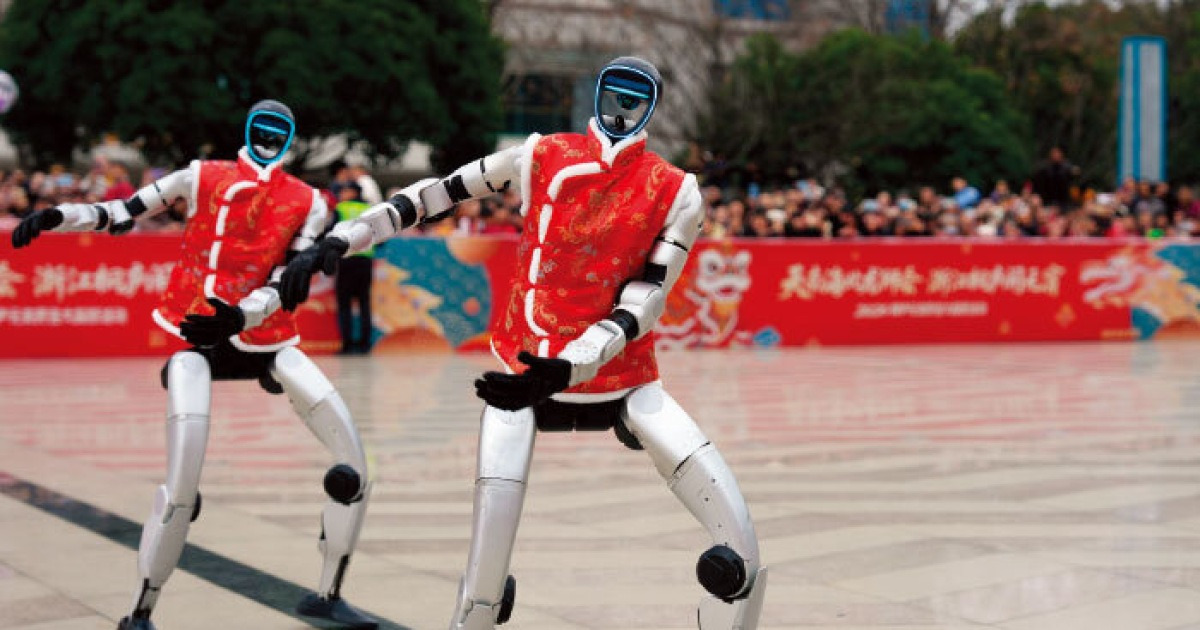
Ubtech’s 629% debut was never about the stock. It was about the signal.
On August 19, China’s Ubtech Robotics opened for trading on Shanghai’s ChiNext board and immediately detonated. The share price surged 629.44% in the first minutes of trading, pushing the company’s market cap to 444.9 billion yuan—roughly $61.8 billion—at a price-to-earnings ratio of 219. The second day saw a 18.7% pullback, but the initial spike told the real story: nearly 9.78 million individual investors placed bids, creating a subscription ratio of 5,526 to one. Their total order volume exceeded 8.1 trillion yuan, eclipsing even the previous record set by memory chipmaker CXMT just weeks earlier.
Ubtech raised 6.1 billion yuan in the offering, committing the proceeds to AI model research, new product development, and expanded manufacturing capacity. It already holds roughly 32% of the global humanoid robot market by shipment volume, delivering 5,511 units in 2024 alone. But the more interesting question isn’t who is buying Ubtech shares. It is who designed this listing to begin with.
The IPO pipeline is a policy tool
China’s Securities Regulatory Commission began actively steering technology companies toward the ChiNext board in mid-2024, when it announced eight measures to deepen the market’s reform. The policy message was unambiguous: firms with innovative capabilities would be welcomed even if they were not yet profitable. The rationale was blunt—advanced technology sectors require enormous capital, and their R&D-to-commercialization pathway is inherently uncertain. Waiting for profitability before listing would mean waiting too long.
The mechanism that made Ubtech’s listing possible is called the pre-review IPO system, introduced last year. Companies can submit their materials to regulators under confidentiality, receive feedback, and revise before filing formally. This compressed Ubtech’s entire registration process—from initial application to CSRC approval—to just 104 days. For comparison, the 39 companies registered by the CSRC in the fourth quarter of 2024 averaged 393 days. Ubtech’s predecessor, CXMT, took 148 days and was only the second company to use the pre-review track.
This speed did not emerge from administrative efficiency. It reflected political priority. Ubtech and CXMT were the first and second wave of firms explicitly chosen to benefit from the compressed timeline. In Beijing’s calculus, these are not ordinary listings. They are strategic deployments of capital markets toward technological sovereignty.
Red Tech as state doctrine
The term Red Tech has entered Chinese policy discourse as a shorthand for the strategy of building self-reliant, state-aligned high-technology capabilities as a counter to US sanctions and export controls. It operates on two tracks. The first is investment—subsidies, tax incentives, state capital injections, and preferential government procurement aimed at specific sectors. The second is market infrastructure—creating listing pathways, fast-tracking approvals, and directing domestic capital toward target firms.
Ubtech sits squarely at the intersection. It is a humanoid robot maker that has achieved profitability, something rare in a sector dominated by unprofitable peers. Its revenue grew from 159 million yuan in 2023 to 1.7 billion yuan in 2024—a compound annual growth rate of roughly 227%. More critically, 52% of that 2024 revenue came directly from humanoid robot sales, up from just 2% the year before. By vertical integration of core components, the company claims to have driven costs to roughly one-tenth of competing offerings, a position that analysts say has effectively made Ubtech the pricing benchmark for the industry.
This cost advantage is precisely what makes the IPO so useful to the state. A publicly listed robotics champion with an international profile demonstrates that China can scale advanced manufacturing in a sector the United States helped pioneer. That narrative is the point.
Where the strategy frays
The numbers that impress retail investors are also the numbers that alarm analysts. Ubtech’s 219 PE ratio is nearly six times the robotics industry average of 38.56. A larger share of its revenue still derives from non-commercial applications. According to the Chinese economic daily Jingguan Chaobao, research and education accounted for 73.6% of Ubtech’s humanoid robot revenue between January and September last year. Commercial and consumer use made up 17.4%. Industrial and business applications—manufacturing floors, security patrols, warehouse operations—represented just 9%. Of that slice, revenue from actual factory deployment excluding showroom guidance robots was barely 29.3%.
In other words, Ubtech is a leader in robotics that primarily sells to universities, labs, and event organizers. The company is profitable now, but the transition from demonstration equipment to industrial workhorse remains unproven. If that transition stalls, the current valuation has nowhere to go but down.
There is also a more immediate constraint. In July, the US Federal Communications Commission banned the import of Ubtech’s products along with other foreign-made humanoid and quadruped robots, citing national security concerns. The US market accounted for 13% of Ubtech’s total revenue in 2024. A formal export restriction or further sanctions could erode that figure significantly. Ubtech’s listing on Shanghai’s board does not protect it from Washington’s regulatory reach.
The Korean angle nobody is discussing
South Korean investors cannot buy Ubtech directly. The shares trade as an A-share, available only to domestic Chinese investors. The South-North Connect corridor—the mechanism that allows overseas investors to trade mainland shares through Hong Kong—has not designated Ubtech as an eligible stock, and it is unlikely to do so in the near term given the listing’s recent date and the liquidity thresholds involved.
But Samsung Asset Management is preparing a workaround. Its KODEX China Humanoid Robotics ETF already expanded its underlying index from a South-North Connect-only universe to cover the entire Chinese equity market in February, and adopted a Fast Entry mechanism that allows new listings to be added outside the regular review cycle. A company representative confirmed that if Ubtech meets the index methodology requirements, it could be incorporated into the ETF as early as September 2.
This matters because it shows how quickly global capital is being rerouted toward Chinese strategic sectors precisely when Western markets are closing off. South Korean institutional investors will gain indirect exposure to Ubtech without crossing any compliance boundary that US regulators would scrutinize. The ETF structure exists in a regulatory gray zone—not direct ownership of a sanctioned Chinese firm, but not disconnected from it either. It is capital channeling at its most opportunistic.
What happens next
Ubtech’s listing completes a loop that China has been building for years. The state identified a sector where American firms held early advantage, designed policy tools to accelerate domestic competitors, directed subsidized capital toward the chosen champion, and then used the capital markets to legitimize and fund further expansion. The humanoid robot is the current flagship of this project—a sector that combines AI, advanced manufacturing, and a visible consumer product that can be demonstrated at scale.
The risk to the model is real. Ubtech’s current revenue base depends heavily on non-industrial buyers. The US ban removes a meaningful market. The PE ratio leaves little room for disappointment. But none of this changes the direction of travel. China will keep compressing IPO timelines for strategic sectors. It will keep creating ETF wrappers that allow indirect foreign exposure to Chinese champions. And it will keep treating capital markets as infrastructure for technological sovereignty rather than as neutral venues for price discovery.
The global robotics supply chain is not simply moving away from the United States. It is fragmenting into distinct ecosystems—one anchored in American design and software, the other in Chinese manufacturing scale and state-capitalist coordination. Ubtech’s listing is the clearest signal yet that Beijing considers this second ecosystem mature enough to present to the world.