Washington Is Now Telling Tokyo How to Manage Its Currency
The US Treasury publicly urged Japan to take aggressive monetary action against yen weakness—a rare diplomatic signal that reframes US-Japan economic relations. It also leaves the Bank of Japan caught between domestic credibility and American pressure.
Washington has stopped whispering.
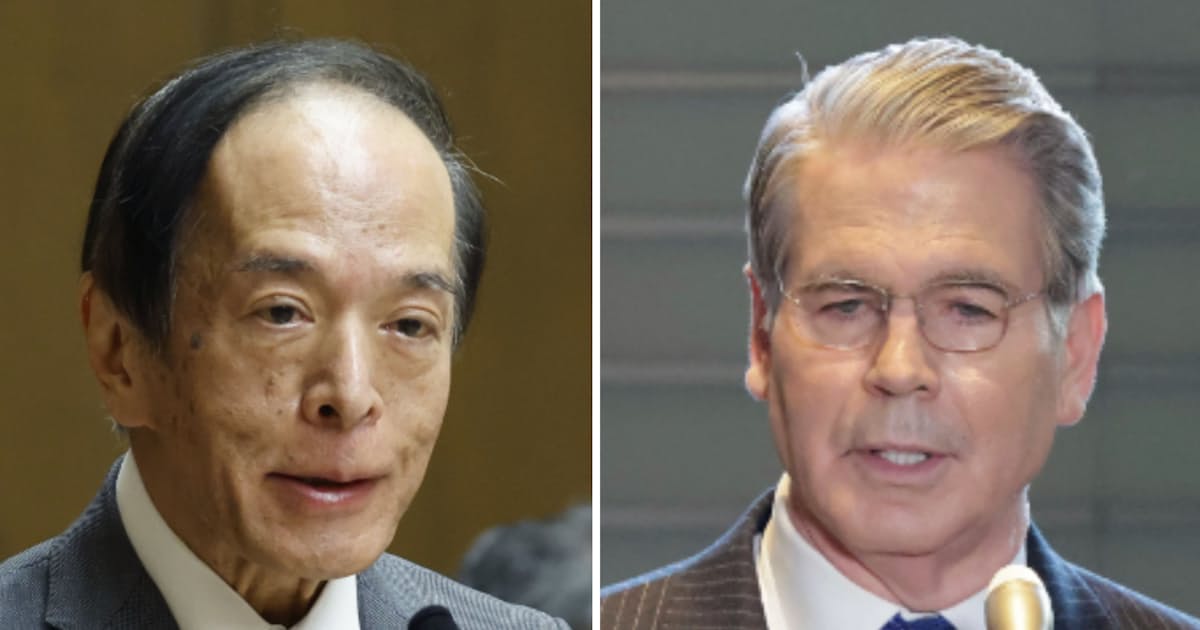
On August 30, at a G20 ministers’ meeting in Ashville, North Carolina, US Treasury Secretary Scott Bessent sat down with Bank of Japan Governor Kazuo Ueda and delivered a message that the Japanese side would not have expected to hear from across the Pacific so directly. The yen was being undervalued. Japan needed to act—resolutely, firmly, on both market and monetary policy fronts—to stop it.
The US Treasury released the meeting readout on September 1. The language was careful but unmistakable: Bessent stressed the importance of sound monetary policy formulation and communication to anchor inflation expectations and avoid excessive exchange rate volatility. Translated into policy terms, that meant the BoJ should raise rates sooner rather than later and signal willingness to keep going.
What makes this moment noteworthy is not the substance—Washington has long preferred a stronger yen—but the delivery. A public readout from the Treasury Department naming the BoJ governor and laying out specific policy expectations is a departure from the usual private channels. It turns a bilateral economic conversation into a documented signal, visible to markets, to allies, and to domestic critics in both capitals.
The precedent is thin. Since the Plaza Accord of 1985, US pressure on Japanese monetary and exchange-rate policy has almost always been exercised through back-channel diplomacy or multilateral forums where direct attribution is murky. This readout, with its plain-language framing, effectively places the BoJ on notice in a manner that mimics the diplomatic posture once reserved exclusively for emerging-market economies. That shift in tone is itself a policy signal.
Who wins, who loses, and who gets squeezed.
The immediate loser is the Bank of Japan’s credibility. Ueda has spent years building the central bank’s independence from political and external interference. A public request from the US Treasury for Japan to tighten policy on currency grounds complicates that narrative enormously. If the BoJ raises rates next month, markets will ask whether the decision was driven by domestic inflation dynamics or by Washington’s timetable. The answer will shape the yen’s trajectory and the BoJ’s standing for years.
Already, sovereign yield spreads have begun to reflect the tension. The 10-year JGB-Treasury spread tightened by roughly eight basis points in the session following the readout, as traders priced in a higher probability of a September hike. But that same pricing embeds a risk premium: if the market concludes the move is externally motivated rather than organically warranted, the yen’s rally may prove short-lived and the BoJ’s credibility further eroded.
Japan’s government faces a different constraint. As LIFULL HOME’S researcher Nobutaka Nakayama noted in commentary on the meeting, Japan’s annual debt-servicing costs on government bonds now exceed 160 trillion yen—larger than the country’s entire annual budget. That number matters to Washington almost as much as to Tokyo. A weaker yen imports inflation and forces the BoJ to choose between letting inflation run hot or raising rates into a fragile fiscal position. The US benefits from a stable yen because it reduces pressure on American Treasury yields. Japan benefits from stability too, but the political optics of appearing to comply with American demands are corrosive.
The second-order political effect is already visible in Tokyo’s parliamentary discourse. Opposition lawmakers have seized on the readout as evidence that the Kishida cabinet has surrendered monetary sovereignty. Even members of the ruling LDP’s policy council have privately expressed discomfort with the public framing. That friction will intensify if the BoJ proceeds with a rate hike that appears causally linked to Washington’s statement rather than to Japan’s own data.
Carry traders, meanwhile, now face a new variable. The yen’s depreciation has been sustained in part by the interest-rate differential between Japan and the United States. Bessent’s public push for faster BoJ tightening narrows that differential sooner than some market participants priced in. If the central bank moves ahead of schedule, the unwind of yen-funded positions accelerates. The question is whether the market anticipated this or whether the Ashville meeting catches positioning off-guard.
Positioning data from CFTC reports shows hedge funds maintain net-short yen positions at levels not seen since early 2024. A sudden policy pivot could trigger a convex unwind—fast enough to compress bid-ask spreads and generate whipsaw volatility in FX options. The vol-of-vol index for USD/JPY spiked 14% on the day of the readout release, suggesting the market is already bracing for a regime shift rather than a gradual one.
The policy trap.
Ueda has raised rates five times since the BoJ ended negative interest rates. Each 0.25 percentage-point move has had limited effect on the exchange rate. The reason is structural: the yen’s weakness is not solely a monetary policy problem. It reflects Japan’s chronic current-account surplus dynamics, demographic drag on savings, and the sheer scale of Japanese institutional investors’ overseas allocation. A rate hike alone does not reverse those forces.
Nakayama’s analysis raises a pointed question: if conventional rate increases have not moved the yen, what remains? Direct intervention? Qualitative shifts in yield-curve control framing? Capital inflow incentives? Each option carries its own risks. Intervention drains foreign reserves. Tweaking communication can backfire if markets interpret it as desperation. Structural reforms take years. The BoJ is effectively being asked to solve a problem that no single tool can fix, and to do so on a timeline set outside its borders.
There is also a less obvious trap. The readout implicitly treats the yen’s weakness as a policy failure rather than a market outcome. But the currency’s depreciation has, in important channels, been supportive of Japan’s export-oriented sectors and of corporate earnings. Some of the largest Tokyo-listed firms have reported record margins precisely because the weak yen boosts the dollar value of their overseas profits when translated back. A rapid yen appreciation triggered by externally pressured rate hikes could compress those margins and feed directly into a domestic growth slowdown—precisely the outcome the BoJ has been trying to avoid.
That tension is likely to surface in the minutes and policy statement following the BoJ’s next decision. If Ueda frames the next move as data-dependent while quietly acknowledging external pressures, he preserves plausible deniability. If he explicitly references exchange-rate stability as a factor, he concedes that Washington’s framing has penetrated the central bank’s communication strategy.
What happens next.
The BoJ will meet later this month. Markets will watch for two signals: whether the central bank raises rates again, and whether it addresses the Treasury’s concerns in its statement without appearing to echo them. A quiet hike—framed as domestically warranted—would satisfy Washington without surrendering independence. A pause would invite further public pressure. Either outcome reshapes the yen’s path.
For the broader market, the Ashville readout is a reminder that the yen will not be allowed to depreciate without a fight from Washington. That floor changes the calculus for every portfolio with yen exposure. The carry trade, once a reliable source of return in a low-rate world, now operates under a ceiling as much as a floor. When the US Treasury speaks publicly about yen policy, the question is no longer whether the BoJ will tighten—it is how much tightening is enough, and whether Japan’s economy can absorb it without stalling recovery.
The deeper implication is about alliance economics. The US-Japan relationship has always contained a monetary component, but it was typically managed behind closed doors. Public framing changes the game. It gives domestic audiences in Japan a target for criticism and gives the BoJ less room to maneuver. It also signals to other US allies—that is, to the ECB, the SNB, and the PBOC—that Washington is willing to name and shame on currency issues when it chooses to. The normative boundary between private coordination and public pressure has been redrawn, and the new line favors the issuer of the reserve currency.
For now, the yen will react to what traders think the BoJ will do next. But the real story is the shift in who gets to decide.