The $40 Trillion Debt Tipping Point: Why Growing Out of It Won't Work
US national debt crosses $40 trillion milestone, doubling in a decade. Treasury claims spending fuels growth, but economists warn structural deficits and rising debt-servicing costs make simple expansion insufficient to clear the burden.
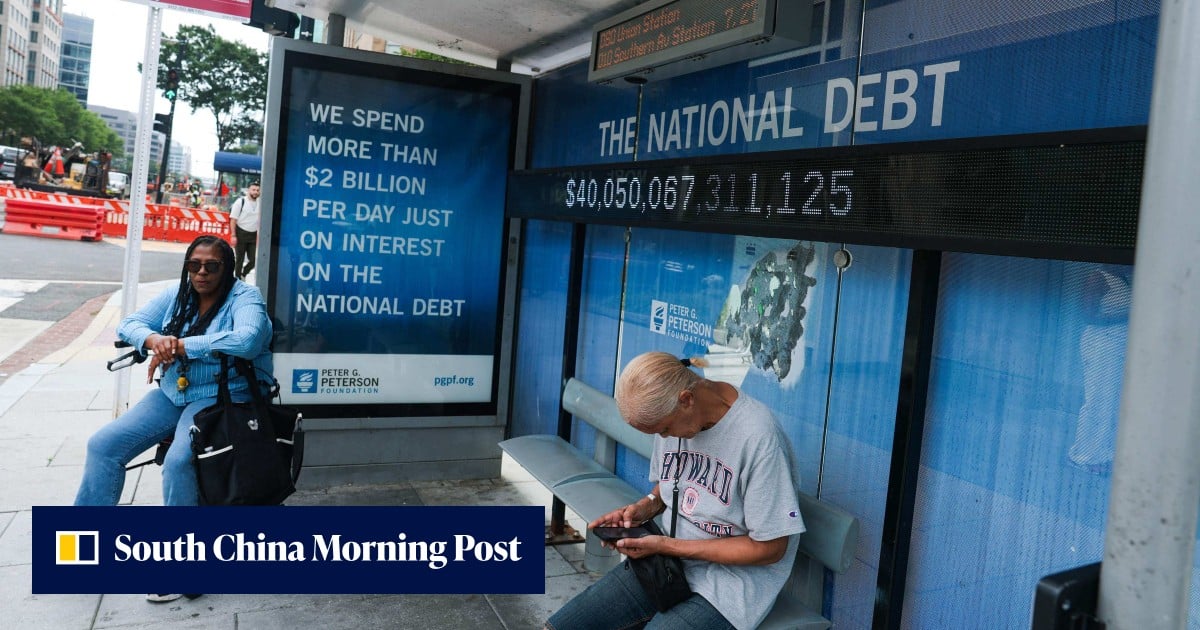
The Milestone That Isn’t Just a Number
The United States crossed $40 trillion in national debt last week. The figure arrived quietly, without the fanfare of a stock market peak or a geopolitical crisis. Yet it marks a threshold that reconfigures the financial landscape beyond Washington’s borders. Debt has doubled over the past decade. Since 2022 alone, the US added another $10 trillion—a pace that would have been unthinkable even three years ago.
The average American household now bears a per-capita share exceeding $120,000 when counting both public debt and intergovernmental obligations. These are not abstract statistics. They represent claims against future production, future tax revenue, and future policy choices. The sheer magnitude distorts every debate about healthcare, defense, infrastructure, and Social Security. Congress cannot fund these priorities at current levels without issuing more debt, which in turn requires higher interest payments, which consume more of the budget. The cycle is self-reinforcing.
The reaction from Treasury officials was swift. Secretary Scott Bessent told CNBC that much of the borrowing financed investments in factories and equipment, arguing the country will “grow our way out” of the mountain. The logic rests on a familiar premise: historical GDP growth has always kept pace with fiscal expansion, and nothing fundamental has changed. Japan, after all, carries debt exceeding 250 percent of GDP without crisis. Why should America fare worse?
The Flaw in the Growth Narrative
Alicia Garcia-Herrero, chief economist for Asia-Pacific at Natixis, disputes the assumption. She notes that despite high nominal growth rates in recent years, the US continued accumulating debt at an accelerating pace. The crucial distinction is between nominal and real growth. Inflation has buoyed headline figures, masking the reality that spending outstrips revenue even during expansionary periods. When GDP rises 5 percent but the deficit grows 8 percent, the debt ratio deteriorates regardless of how robust the growth sounds in press briefings.
The structural barriers are clear and compounding. Government expenditure remains elevated across nearly every category—mandatory spending on entitlements alone now exceeds $3 trillion annually. Debt-servicing costs climb as interest rates stay above the low-single-digit averages that dominated the prior decade. Tax cuts enacted in 2017 and extended thereafter reduced revenue without corresponding spending cuts. Together, these factors create a fiscal posture that growth alone cannot neutralize. Even if the economy expands at 3 to 4 percent annually—a optimistic assumption given demographic headwinds and declining productivity growth—the debt-to-GDP ratio will not fall unless primary surpluses emerge. The current trajectory points toward persistent deficits averaging 5 to 6 percent of GDP through the decade.
What makes this particularly dangerous is the erosion of fiscal space. During the 2008 financial crisis and the 2020 pandemic, the US could borrow aggressively because rates were near zero. Today, servicing existing debt consumes roughly $1 trillion annually—more than the entire defense budget. Any additional shock, whether a financial crisis, a war, or a natural disaster, will force choices between catastrophic borrowing or sudden spending cuts. Neither is politically survivable.
Who Loses When Debt Compounds
The consequences extend beyond balance sheets. Rising debt-servicing costs crowd out discretionary spending on infrastructure, education, and defense. They also limit fiscal flexibility during downturns. When the next recession arrives, the government will face a choice between deeper borrowing or painful austerity. Either path carries political and economic costs. Markets may reward temporary stimulus, but they punish chronic irresponsibility—and the distinction between the two is often invisible until it is too late.
Internationally, the implications are more diffuse but no less significant. The dollar’s reserve currency status depends on confidence in US fiscal management. Every additional trillion in debt tests that confidence. Foreign holders of US Treasury securities—China holds approximately $800 billion, Japan roughly $1.1 trillion, and collective emerging-market central banks another $500 billion—watch closely. None of these holdings are small enough to single-handedly trigger a crisis, but their behavior is interconnected. If one major holder reduces purchases or sells, others interpret it as a signal. A loss of faith could trigger capital flight, higher yields, and dollar depreciation—a scenario that would ripple through global trade and commodity markets, raising costs for import-dependent nations and destabilizing exchange rates.
The Emerging Market Exposure
Emerging markets hold substantial US debt, often denominated in dollars. A weaker dollar or higher US rates increases their refinancing costs and amplifies currency mismatches. Countries that borrowed heavily during the pandemic era—Argentina, Egypt, Pakistan, Ghana—now face a dual challenge: servicing domestic debt while absorbing external shocks from American fiscal instability. The interconnection works both ways. A disorderly adjustment in US debt markets would force emerging economies into defensive postures, reducing their ability to invest in growth and pushing vulnerable populations toward hardship. Capital would flee riskier assets, commodity prices would collapse, and the very institutions the US helped build—IMF programs, bilateral swap lines—would face strain beyond their design capacity.
Why the Conversation Is Shifting
The debate has moved from whether the debt is a problem to how severe it will become. Ten years ago, economists discussed the possibility of a fiscal crisis. Today, they examine scenarios and policy trade-offs. The milestone has normalized the scale of borrowing while sharpening the focus on sustainability. Policymakers can no longer defer the question indefinitely, even if political incentives still reward deferral.
Garcia-Herrero’s critique highlights a broader consensus among macroeconomists: growth is necessary but insufficient. Without reforms to revenue or expenditure, debt will continue to compound. CBO projections under current law show the debt-to-GDP ratio reaching 140 percent by 2035, up from roughly 97 percent today. The timeline matters. Each year of delay increases the likelihood of a sharp adjustment rather than a gradual deleveraging. Markets may tolerate high debt levels for extended periods—Japan proves that—but tolerance is not infinite, and the mechanism of adjustment when tolerance finally breaks is rarely gentle. Sudden yield spikes, currency crises, and forced austerity tend to arrive together.
What Comes Next
The immediate future likely involves more borrowing. With tax cuts enacted and spending protections intact, there is no political incentive to reduce deficits. The Treasury will issue more debt, and investors will absorb it as long as demand remains steady. However, the cost of that demand rises. Auction results show increasing yield sensitivity, suggesting that marginal buyers require higher compensation for each additional tranche. Foreign demand has softened. Domestic institutional buyers—pension funds, insurance companies, mutual funds—face regulatory and balance-sheet constraints that limit their appetite. The Federal Reserve, once a reliable backstop, has shifted from quantitative easing to quantitative tightening, removing a major source of demand.
Beyond Washington, the $40 trillion milestone serves as a benchmark for stress-testing financial systems. Banks hold significant Treasury portfolios as high-quality liquid assets. Pension funds rely on fixed income for liability matching. Asset managers price risk based on yield curves that reflect fiscal expectations. Any disruption to this ecosystem could propagate quickly. A disorderly sell-off would not remain contained within sovereign debt markets. Money market funds, commercial paper, and repo markets all touch Treasury securities. Contagion, while not inevitable, becomes plausible once thresholds are breached.
The Bottom Line
The US debt gamble is no longer hypothetical. The numbers are stark, and the assumptions underlying the “grow out of it” argument are fragile. Growth helps, but it does not solve structural imbalances. It buys time. It does not create a path. The global economy depends on American fiscal discipline more than ever. When the world’s reserve currency issuer accumulates debt faster than it accumulates assets, everyone shares the risk—whether through higher borrowing costs, weaker currencies, or compressed returns on safe assets.
Economists like Garcia-Herrero are right to sound the alarm. The conversation has shifted from denial to urgency, from abstract modeling to concrete stress scenarios. The question now is whether policymakers will respond with courage—raising revenue, restraining entitlement growth, restoring credibility—or continue borrowing until the market forces their hand. History suggests the latter path is far more common, and far more costly, than political rhetoric admits. At $40 trillion, the US is no longer testing the limits of fiscal sustainability. It is living inside them.