Apple's iPhone Duo Delay Shows Supply-Chain Fragility
Apple's foldable iPhone faces massive demand but can't keep up with production. The shipping delay exposes how much Apple depends on fragile manufacturing pipelines—and how rivals could win by simply being ready first.
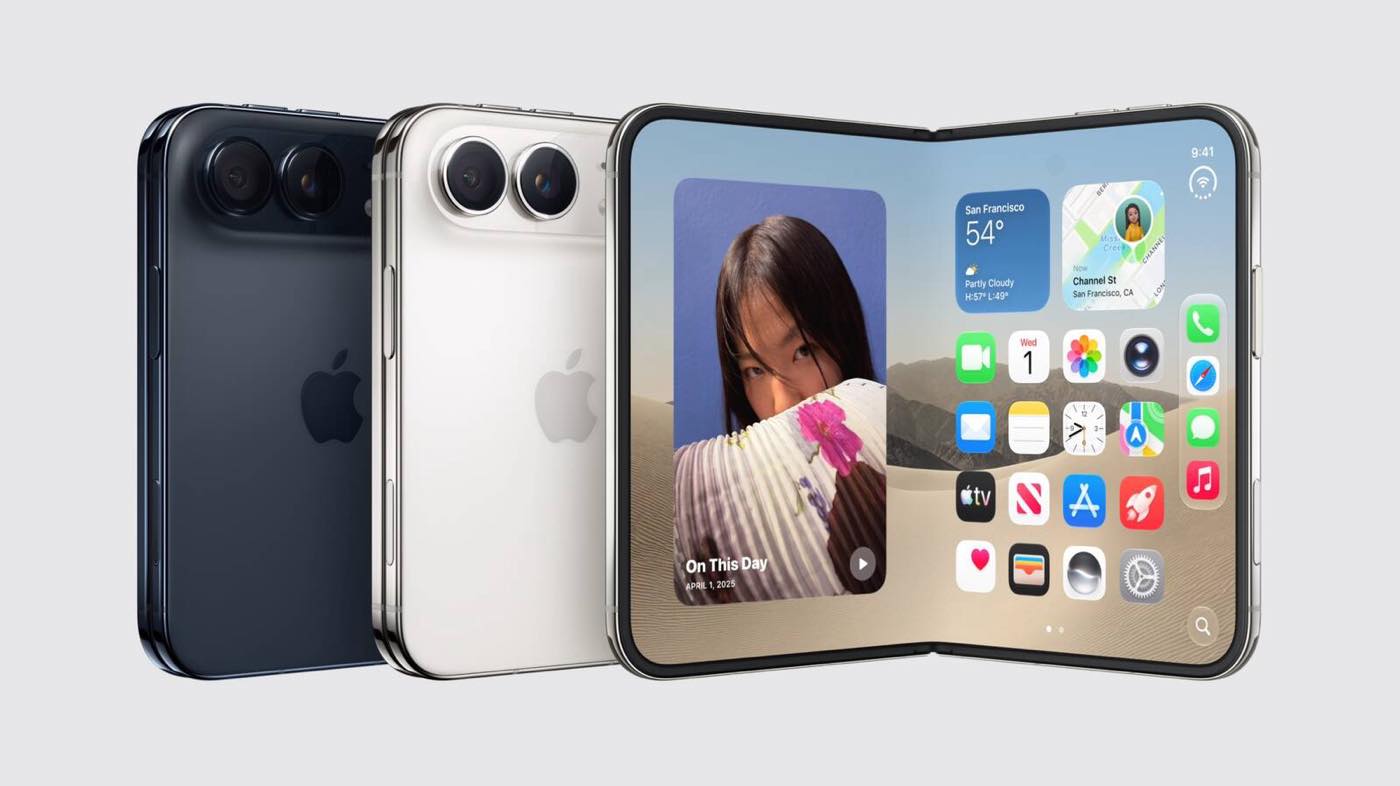
The Foldable That Can’t Be Folded Into Existence
Apple announced its first foldable phone in what the company calls extraordinary demand, and then promptly could not build enough to satisfy it. The iPhone Duo, long rumored as the tech industry’s most anticipated device, began shipping only after major delays pushed delivery into late January and early February 2027—months past where consumers expected to receive it.
The company described reservation demand as “truly extraordinary” in a statement to CNBC, then added something that should have been obvious: it was working to deliver the product as quickly as possible while continuing to accept online orders. The phrasing mattered less than the reality it concealed—Apple could not move fast enough.
Japan’s delivery schedule sits at January 23, 2027. Brazil extends to early February. eBay and X listings already show resellers offering the phone for up to $10,000—roughly 1.6 million yen. These are prices that belong to speculative bubbles, not mainstream electronics launches.
What makes this delay particularly damaging is the timing. Apple has positioned the iPhone Duo as its answer to years of foldable skepticism from analysts and investors. Tim Cook himself called it “the biggest innovation in the iPhone’s history” during the unveiling. For a product carrying that level of rhetorical weight, the inability to fulfill pre-orders on schedule signals something deeper than a production hiccup. It suggests Apple may have fundamentally misread how long it takes to scale a category it does not yet own.
The waitlists that formed overnight on Apple’s website were not merely a marketing success story. They were also a promise the company could not keep. Every day a consumer waits past an expected delivery date, brand trust erodes slightly. The psychological contract between Apple and its customers has always been: order early, receive quickly. That contract is now in question.
Why Apple’s Shortage Is Not Just an Apple Problem
The iPhone Duo delay exposes something structural about how Apple’s supply chain now works. This is not a company that manufactures its own screens, assembles its own devices, or controls its own production schedule in the way Samsung does. Apple designs. Foxconn and its partners build. LG and Samsung Display provide the foldable OLED panels. Apple’s role is increasingly that of orchestrator rather than owner.
When that orchestra hits a snag—and foldable displays remain one of the most difficult products to mass-produce at scale—the entire delivery timeline slips. The iPhone Duo’s fold mechanism requires precision engineering that current manufacturing processes simply cannot match at the volume Apple demands. Yield rates on foldable panels are low. The defect rate per batch is higher than Apple’s traditional phones. This means fewer working units per production run, longer assembly times, and a schedule that cannot compress.
Apple’s dependence on Chinese manufacturing adds another layer. While the company has attempted to diversify production into India and Vietnam, the infrastructure for complex foldable assembly remains concentrated in China. The iPhone Duo likely requires production lines that simply do not exist at sufficient scale anywhere else. Foxconn’s facilities in Zhengzhou and Shenzhen have spent decades perfecting the assembly of rigid devices. The skills, tooling, and supplier ecosystems required for foldable production are newer, rarer, and still being built.
The second-order effect of this bottleneck is significant. Apple’s other product lines—the Mac, the iPad, the standard iPhone models—depend on the same supplier relationships, the same logistics corridors, and often the same factory floors. When Apple prioritizes iPhone Duo production, it may be pulling resources away from existing products that generate far more revenue. This creates a ripple effect across the company’s entire hardware business, not just the foldable segment.
Analysts at Morgan Stanley noted that Apple’s supplier network is showing signs of strain not just from the iPhone Duo but from concurrent production increases across multiple categories. The company is essentially trying to scale three different product lines simultaneously while simultaneously trying to enter an entirely new form factor. The organizational bandwidth required for that effort exceeds what even Apple’s legendary supply-chain management has historically delivered.
Who Wins From This Delay
Samsung wins. It already ships foldable phones at scale. The Galaxy Z Fold and Z Flip series occupy the market Apple is attempting to enter, and Samsung’s production capacity is mature. Every month Apple delays, Samsung’s installed base grows and its next-generation foldable line gains credibility with consumers who need a working product now.
Samsung’s advantage extends beyond production. The company has been iterating on foldable technology since 2019. Its engineering teams have had nearly eight years to refine hinge mechanisms, improve display durability, and reduce manufacturing costs. Apple is attempting to compress that timeline into roughly two years of focused development. The gap between those timelines is visible in every specification sheet and every review.
Chinese manufacturers win in a different way. Huawei, Xiaomi, and Oppo all ship foldable devices in China. Huawei’s Mate XT and other models have captured domestic market share. If Apple’s iPhone Duo remains delayed, those brands gain time to solidify their position before Apple’s entry disrupts the market.
Huawei deserves particular attention here. The company’s foldable phones, while not available in Western markets at scale, have demonstrated impressive engineering and are gaining traction in China’s premium segment. A delayed iPhone Duo gives Huawei an extended window to deepen its hold on Chinese consumers before Apple can challenge it globally. This is not hypothetical—recent Canalys data shows Huawei’s foldable shipments growing faster than Apple’s total iPhone volume in several Chinese provinces.
Resellers win immediately. The $10,000 listings on eBay and X are proof of a market willing to pay extreme premiums for products it cannot obtain through normal channels. Apple’s scarcity creates arbitrage opportunity, and someone always captures that value.
What distinguishes this resale market from typical scalper behavior is the sustained demand. This is not a limited-drop phenomenon where prices collapse after initial novelty fades. The iPhone Duo represents a category-defining device, and the secondary market reflects genuine consumer desperation rather than speculative curiosity. As long as the primary market remains constrained, the secondary market will extract outsized margins.
The Criticism That Should Matter More
Criticism of Apple’s reservation system has emerged, with some consumers calling for the company to cancel orders suspected of being placed by resellers. This is a legitimate concern. The resale market that forms around any scarce Apple product represents a redistribution of value away from the company and toward intermediaries.
But this criticism misses the larger point. Apple’s inability to prevent resales is not a policy failure—it is a production failure. The company would need to produce more units to eliminate the secondary market entirely. Canceling orders does not increase supply. It only redistributes existing inventory among verified buyers rather than verified buyers and speculators.
Apple’s account-verification system, which requires phone numbers and payment methods tied to individual identities, is technically sophisticated but ultimately a filtering mechanism, not a supply solution. The real fix would involve ramping production to meet actual demand, which returns us to the fundamental bottleneck: Apple does not yet know how to build enough iPhone Duos.
There is also a strategic dimension to the reseller problem. Some analysts argue that Apple could quietly benefit from the secondary market by using resale prices as a demand signal. If $10,000 is what consumers are willing to pay on eBay, the implication is that Apple may have priced the device too conservatively—or at minimum, that demand was significantly underestimated. Whether Apple will internalize that lesson remains unclear.
What Happens Next
The iPhone Duo will ship. It will sell. The question is not whether Apple can deliver a foldable phone—it is whether it can deliver enough of them, fast enough, to matter strategically. Every month of delay is a month Samsung occupies the narrative around foldable technology without challenge.
Apple’s supply chain advantage, historically its greatest competitive weapon, now appears as a vulnerability. The company designs for margin and precision, not for speed and redundancy. When demand exceeds capacity, the response is always the same: delay, not expand. This is a pattern that will repeat until Apple changes how it approaches production scaling.
The foldable phone market is growing. Consumer adoption is accelerating. Chinese manufacturers are investing heavily in foldable display technology. Apple’s competitive advantage in the smartphone market depends on being first or being best—or both. The iPhone Duo delay suggests Apple may be neither at the moment it needs to be.
One scenario worth considering is that Apple uses this delay to its advantage. By extending the wait time, the company may be deliberately managing launch momentum—keeping anticipation high while avoiding the disappointment of rushed production quality. This is a plausible interpretation, but it does not change the fact that competitors are gaining ground during the waiting period. Every month of silence from Apple is a month of marketing from Samsung and Huawei.
Another possibility is that Apple accelerates production ramp in 2027, leveraging the initial demand surge to secure priority access to display panels and component supplies from LG and Samsung Display. If Apple can convert the iPhone Duo into a volume seller comparable to the standard iPhone lineup, its suppliers will have strong incentive to prioritize its orders. But that conversion is not guaranteed, and the window for securing supply commitments is narrowing.
For now, the extraordinary demand Apple describes is real. The extraordinary shortage is also real. The gap between them is where the company’s next strategic problem lives—and where its competitors are already positioning themselves to exploit it.