Korea's Crash Signal: Forced Liquidations Surge 4x as Delisting Plays
Forced liquidations in Korea jumped nearly 4x as the KOSPI shed over 20% in a week — yet delisting-risk stocks are rallying like hot IPOs. The contradiction is a warning sign for every emerging-market portfolio with Korean exposure.
The numbers that should keep emerging-market fund managers awake
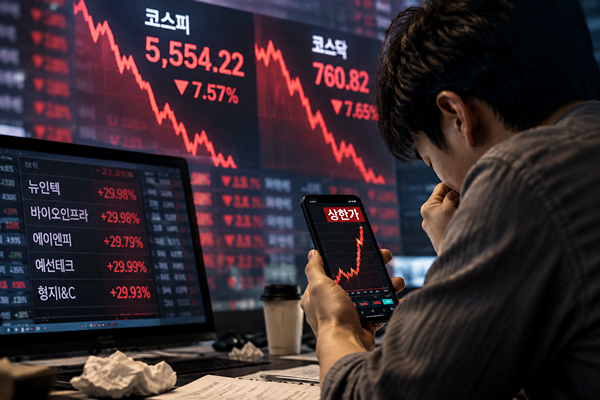
Korea’s stock market just executed a violent unwind that most international portfolios had underpriced. Between the 6th and 15th, the KOSPI shed 1,449.52 points — a 20.70% freefall in seven trading days. The KOSDAQ followed a day later, dropping 159.10 points or 17.29% over six sessions. On the 15th itself, both indices crashed roughly 7.6%, triggering circuit breakers simultaneously across both markets for the first time in this sell-off.
The breadth was devastating. Of the 940 KOSPI-listed stocks, 777 finished in the red — 82.7% of the universe. On the KOSDAQ, 1,551 of 1,820 stocks fell, a sweep of 85.2%. Eight out of ten Korean equities sold off in a single synchronized panic.
But the headline number for anyone watching cross-border capital flows is the forced-liquidation data. Between the 6th and 15th, brokers executed 298.14 billion won in compelled sell-offs as investors failed to cover margin calls on time. That averages to 42.59 billion won per day — nearly 4x the September daily average of 10.96 billion won. Half of that entire forced-liquidation volume arrived in two days: 89.34 billion won on the 14th and 80.50 billion won on the 15th. A liquidity spiral, concentrated and brutal.
Investor deposit accounts tell the same story from the other side. Cash on the sidelines — 100.84 trillion won on the 2nd — evaporated to 96.91 trillion won by the 15th. A 3.93 trillion won withdrawal in nine days. Retail investors weren’t just losing paper wealth; they were pulling money out of the system entirely.
The paradox that makes this dangerous
Here is where the story turns from routine volatility into something worth watching internationally. In the middle of a market-wide bloodbath, stocks flagged with delisting risk started rallying — repeatedly, aggressively, absurdly.
Over the same seven-day window, 56 stocks hit their daily price-limit ceiling. Twenty-eight of those hits came from shares teetering on the edge of being delisted for failing market-cap or price thresholds. After stripping out repeated hits on the same names, that leaves 11 individual stocks driving half of all daily limit-ups during a period when 83% of the market was sinking.
Yeseol Tech and Bio Infrastructure each climbed to their daily ceiling five separate times. New Intech did it four times. Even on the 15th — the day circuit breakers fired and panic was at its peak — three of the six limit-up stocks were delisting-risk names: New Intech, Bio Infrastructure, and A&N Pharma.
This is not a rational allocation of capital. These are companies that should be selling off hardest in a crisis. Instead, they became the most wanted stocks in Korea.
The court that accidentally became a speculative catalyst
The mechanism behind the delisting rally is institutional confusion, and it started with a court decision most foreign investors likely missed.
On October 2nd, the Seoul Southern District Court granted a provisional injunction halting the delisting proceedings for Juhyun Tech and KM Pharma. The legal basis centered on two issues: whether the exchange had acted too quickly in strengthening its market-cap delisting thresholds, and whether the companies’ procedural rights had been properly observed. The court said they had not been.
Korea Exchange’s response was to freeze further delisting procedures for market-cap-driven violations while keeping those companies on the watchlist. Price-based delisting rules — the ones tied to share price rather than total market value — remained untouched.
That half-measure created a loophole that speculators exploited immediately. If the exchange is not enforcing delisting for market-cap failures, then delisting-risk stocks are no longer death traps — they are binary bets on institutional inertia. The market-cap delisting fear evaporated for some names. The price-delisting risk remained. Stocks caught between both criteria, like New Intech and A&N Pharma, kept hitting ceilings because investors bet that any delay in enforcement buys enough time for a turnaround or a regulatory reprieve.
An industry source told News Today the pattern is clear: during a market already saturated with risk-aversion, the judicial pause on delisting has become a shared thematic driver for high-risk names. The contradiction is that the very uncertainty meant to protect companies from rushed exits is now fueling speculation that makes those companies’ shareholders richer while their fundamentals deteriorate.
Who wins, who loses, and what happens next
The winners in this structure are narrow and dangerous. Speculative retail traders who entered delisting-risk names after the court decision have made asymmetric gains while the broader market bled. The 11 stocks that generated 28 limit-ups during a 20% market crash extracted wealth from every investor who held them, sold at a loss, or withdrew deposits in panic.
The losers are the margin-called investors whose positions were forcibly liquidated — 298 billion won in compelled selling is not an abstract figure. That is real money exiting real accounts under duress. And it is the same pool of investors who are now tempted back in through delisting-risk speculative plays, creating a feedback loop that amplifies both the crash and the bubble sitting inside it.
For emerging-market portfolios, the lesson is structural rather than incident-specific. Korea is one of the few EM markets where retail leverage, circuit-breaker mechanisms, and delisting enforcement interact in real time under stress. When margin calls accelerate 4x in a week and delisting-risk stocks rally on judicial uncertainty instead of fundamentals, the usual diversification arguments break down. The whole market moves together, and the exceptions prove the rule.
What happens next depends on whether the KRX follows through on its current pause. If the exchange resumes market-cap delistings, the speculative engine powering those 11 stocks will stall abruptly. If it does not, the delisting-theme trade becomes institutionalized — a permanent arbitrage on regulatory hesitation that distorts capital allocation across the entire small-cap segment.
Either way, the forced-liquidation trajectory is the leading indicator. The 298-billion-won number represents selling pressure that has already been realized. The next wave arrives when deposit withdrawals accelerate further, when the 3.93 trillion won pulled from accounts becomes 10 trillion won, and when the next margin call forces another round of compelled selling. The circuit breakers bought time. They did not fix the leverage problem.
For investors outside Korea, the takeaway is simple: this was not a routine correction. It was a leverage unwind with a speculative detour, and the detour is where the contagion risk lives.