Why Koreas Rate Hold Matters More Than It Looks
The Bank of Korea held rates at 3% unanimously, buying time amid global uncertainty — but its own revised forecasts and signaling leave little doubt that more tightening lies ahead.
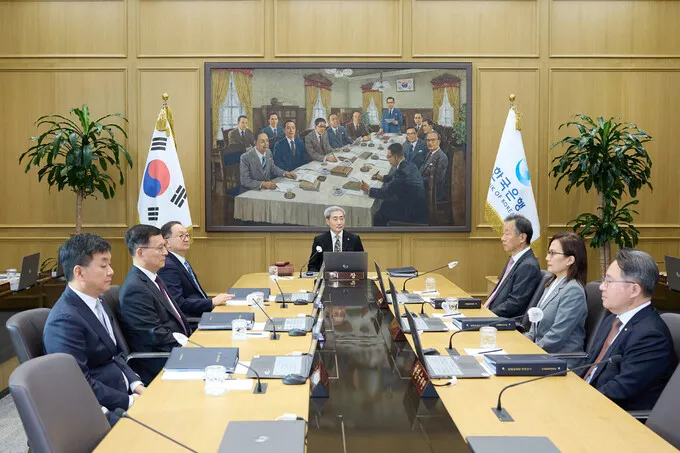
A Pause That Screams Forward
The Bank of Korea delivered exactly what markets feared and hoped for simultaneously: a unanimous hold at 3%, wrapped in language that made clear this was a rest, not a reversal.
Governor Shin Hyun-sung framed the decision as the fruit of prior labor — using the Korean idiom “hoe-blade harvesting,” he described the July and August rate hikes as proactive digging that had bought the economy some room to catch its breath. The won had stabilized, import prices came under control, and low-income households saw a measurable lift in purchasing power from the currency strength.
But read the fine print — or rather, the revised forecasts — and the picture changes sharply.
The Numbers Beneath the Calm
Korea upgraded both this year and next year growth projections significantly above the August estimates. The central bank also forecast that headline and core inflation next year will exceed its August projections of 2.3% and 2.5%. Those are not numbers that coexist comfortably with a dovish stance.
Shin put it plainly: the tightening cycle continues until there is confidence that price growth is sustainably returning to the 2% target.
The implication is clear — the pause is tactical, not philosophical. And the market has already priced much of that in.
What deserves more attention is what those upgrades signal about the internal assessment of Korea’s economy. The Bank of Korea did not merely raise its forecasts; it revised them upward enough to suggest that the soft patch it had previously anticipated was less severe than expected. That reassessment matters because it removes the strongest argument against further tightening — the risk of choking off an already fragile recovery. Instead, the central bank is effectively saying the recovery is holding up, which strengthens the case for continuing to normalize policy.
Whose House Is Heating Up?
Household debt, which had shown signs of easing earlier this year, is accelerating again. Major commercial banks reported a return to lending growth after a brief contraction. Meanwhile, property prices in the outer Seoul suburbs and southern Gyeonggi Province — areas where mid-range homes dominate — are pushing higher on sustained demand.
This is the domestic pressure point that makes Korea’s situation distinct from other advanced Asian economies. The central bank is balancing global uncertainty against a housing market that refuses to cool and a household sector that continues to borrow.
The second-order effect of this dynamic is worth tracking. When household borrowing reaccelerates alongside rising property values, the wealth effect feeds back into consumption. Consumers feel richer, they spend more, and inflationary pressures that the central bank thought it had dampened begin to resurface. This creates a self-reinforcing loop that makes the 2% inflation target harder to reach through rate policy alone, because the very act of allowing credit to flow sustains demand that keeps prices elevated.
For the region, Korea’s data becomes a leading indicator. If Seoul’s households and property market hold up under higher rates, it strengthens the case for other emerging Asian central banks to stay firm. If they crack, the conversation shifts toward growth preservation.
November Comes Fast
The market consensus, according to analysts at Shinhan Investment, now centers on a possible rate increase in November, with the terminal rate potentially reaching 3.50% by early next year. That trajectory assumes the Q3 GDP flash estimate on September 27 and the October inflation data on October 2 both arrive in line with the central bank’s own upgraded outlook.
Given current momentum, that is a reasonable bet. Both indicators have been trending in tightening-favoring directions.
But the path to November is not without friction. Global equity volatility, driven largely by uncertainty around U.S. Federal Reserve policy and ongoing geopolitical disruptions, could create a window where the Bank of Korea feels pressure to demonstrate caution. The question is whether domestic inflation data will outweigh external risk signals when the policy committee meets. So far, the domestic picture has consistently won out — and the upgraded forecasts make it unlikely that pattern will break this time.
The Regional Spillover
Korea’s hold-and-look stance lands at an awkward moment for Asian monetary policy more broadly. China’s economy is still searching for traction, Japan’s gradual shift away from ultra-loose money is creating new pressures across the region, and the Middle East conflict continues to inject volatility into energy and trade routes.
When the Bank of Korea chooses patience, it signals that global risks matter — but its upgraded forecasts signal that domestic inflation is not yet negotiable. That dual message is precisely what makes Korea a bellwether for the region: it shows how middle-income Asian economies are navigating between external fragility and internal price pressures without full clarity on either front.
The spillover extends beyond policy coordination. A higher Korean rate, if it materializes in November, widens the yield differential between Korea and neighboring economies like Japan and China. That puts additional pressure on regional currencies and could force other central banks to adjust their own stances — not because their domestic conditions demand it, but because capital flows respond to relative returns. Smaller open economies in Southeast Asia, already grappling with their own inflation dynamics, may find themselves indirectly locked into a tighter global financial environment simply because Seoul chose to hold.
The Unanimity Signal
The unanimous vote matters more than the headline number suggests. In a period of elevated uncertainty, consensus at the policy committee conveys institutional resolve — exactly the signal a smaller open economy needs when global markets are jumpy. It tells investors that Korea is not behind the curve, nor is it prematurely declaring victory.
Unanimity is not automatic in central banking. Dissenting votes carry weight precisely because they are rare. When every member of the committee agrees, it removes any ambiguity about the direction of policy and forces markets to price in the next move with greater certainty. That certainty itself becomes a constraint — the more the market expects a November hike, the more difficult it becomes for the Bank of Korea to deliver anything less without causing an unwarranted disruption.
What Happens Next
What comes after November will depend on three variables: whether household borrowing continues to climb, whether property prices spread beyond the Greater Seoul periphery, and whether the global risk environment deteriorates further. On all three, the margin for error is shrinking.
The pause was earned. The next move will be harder to justify — not because the Bank of Korea lacks the tools or the courage, but because each incremental step into tighter policy carries compounding costs for an economy that is simultaneously trying to cool a stubborn housing market and avoid breaking a growth story that has outperformed regional expectations. The unified vote signals that Seoul understands this tension. It also signals that it is willing to accept the risk of getting it wrong rather than the risk of staying behind the curve too long.
For investors and policymakers watching from across Asia, the message is unambiguous: Korea’s pause is not a reprieve. It is a breather before the next round begins.