Streaming Giants Unify — And the World Has to Recalculate
Skydance's plan to merge HBO Max, Paramount+, and Discovery+ signals the beginning of the end for the streaming wars. But the implications stretch far beyond American subscribers — it's forcing every international streamer to rewrite its playbook.
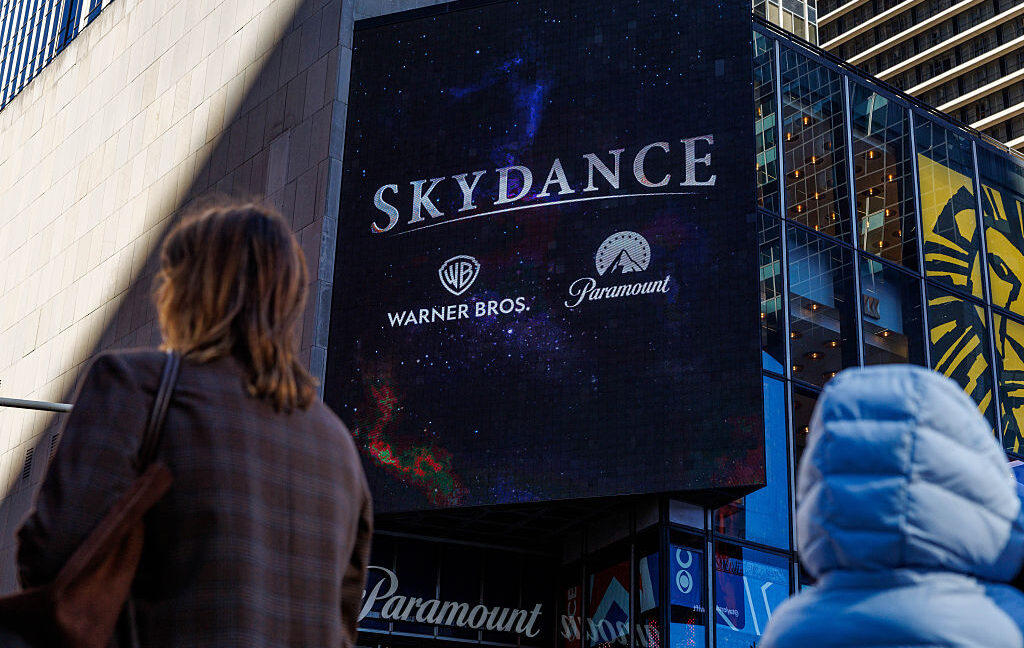
The Streaming Wars Aren’t Ending With a Bang — They’re Ending With a Click
Skydance is consolidating HBO Max, Paramount+, and Discovery+ into a single platform. The headline reads like a corporate press release. The reality is far more consequential.
This isn’t simply about reducing friction for subscribers who currently juggle three different logins. It’s the clearest signal yet that the streaming wars — the period of hypergrowth and fragmentation that defined the last decade of television — are moving toward an abrupt conclusion. What emerges next will determine the economics of content for years, and it will force every streaming service outside the United States to ask uncomfortable questions about their own strategies.
Who Benefits When Three Services Become One
For subscribers, the immediate upside is straightforward. No more switching between three apps to find out whether a show lives on Max or Paramount+ or Discovery+. The recommendation engine becomes dramatically more useful when it can draw on a unified library spanning prestige drama, sports, reality television, and documentary content. A viewer who watches The Last of Us might also get pitched a documentary on survival skills rather than entirely irrelevant programming — that’s the promise.
For Skydance, the gains are even more structural. Running three separate technology stacks, three separate billing systems, and three separate content acquisition teams is expensive. Consolidation eliminates overlapping infrastructure costs and gives the company a single view of consumer behavior across what was previously siloed audiences.
The downside, though, is worth watching closely. A unified platform is likely to prioritize breadth over depth. Shows that appeal to the combined demographics of three services win budget allocations. Programs designed for a narrower, more specific audience — niche international drama, local-language documentary series, art-house cinema — face elimination or relegation to secondary positioning.
Content diversity doesn’t die in a merger. It gets deprioritized. There’s a difference.
The Price Question Nobody Can Answer Yet
Skydance has indicated the move won’t necessarily produce lower subscription fees. This is both predictable and potentially controversial.
When companies consolidate services, they often cite cost savings as a justification — then pass those savings to shareholders rather than subscribers. The streaming industry learned this lesson during the first wave of price increases in 2022 and 2023. Consumers accepted higher prices because the content justification felt real. A merger that doesn’t lower prices risks triggering backlash precisely when the product is supposed to feel simpler and more valuable.
What Skydance may offer instead is a better user experience and more advanced features pulled from each platform’s best technology. That’s a real benefit — but it’s also a harder value proposition to communicate to subscribers who’ve already paid three separate bills.
The Global Ripple Effect
Here is where the story stops being American and starts being worldwide.
The United States is the largest streaming market on Earth. When the three biggest players there consolidate, every other market recalculates. Netflix, Amazon Prime Video, and Apple TV+ all operate globally. They will adjust their content spending, their regional licensing terms, and their launch strategies based on what Skydance’s unified service can offer at scale.
European streamers face an even sharper reckoning. Companies like MGM+ (the European arm), Viaplay, and localized services from Canal+, Netflix’s ad tier experiments, and Disney’s regional offerings must now answer a question they haven’t had to confront clearly: if an American conglomerate can pool an HBO library, a Paramount library, and a Discovery library into one competing product, how does a regional player with a fraction of that content justify its subscription price?
The answer will vary by market. In countries where local-language content commands premium licensing — South Korea with K-dramas, Japan with anime and idiom-driven production, India with regional-language originals — the consolidation gives local streamers an unexpected shield. Skydance’s unified service will struggle to compete meaningfully on local language content without building dedicated infrastructure and acquisition teams in each territory. That’s expensive and slow. Local players who move decisively on domestic originals now hold leverage they didn’t have before.
But in markets where American content dominates — much of Latin America, Southeast Asia, and parts of Africa — the playing field tilts toward the new unified service. Subscribers in those regions will likely see improved bundling options, but they’ll also face a stark choice between a consolidated American offering and fragmented local alternatives.
News Under New Ownership
The merger also brings news into the picture. Through its acquisition of Warner Bros. Discovery assets, Skydance now controls CNN and CBS. Both outlets will operate independently under an Editorial Independence Board — a structure designed to preserve journalistic credibility while consolidating corporate control.
This arrangement mirrors a pattern seen across the media industry: as platforms consolidate, news operations face mounting pressure to align with the commercial interests of their parent company. The Editorial Independence Board is a well-intentioned safeguard, but history suggests that structural incentives matter more than board resolutions. Ad revenue, subscription targets, and corporate strategy will shape editorial decisions whether anyone likes it or not.
Kids’ Channels Without a Clear Strategy
Perhaps the most intriguing unresolved question involves Cartoon Network and Nickelodeon — two rival kids’ networks now under the same corporate roof. Skydance hasn’t said whether it will merge them into a single channel or keep them separate.
The competitive logic says consolidation makes sense. Why run two competing networks aimed at essentially the same demographic? The creative logic says separation preserves brand identity and allows each network to cultivate distinct creative voices. Disney has navigated this tension for decades, keeping channels like Disney Channel and Freeform separate while sharing resources.
Whatever Skydance decides here will signal its broader philosophy about content strategy. Is it optimizing for efficiency, or is it investing in differentiated brands that attract different kinds of audiences?
What Happens Next
The consolidation will take months to finalize. Details will emerge gradually. Subscription pricing, library restructuring, and the fate of individual shows will become clear as the integrated platform takes shape.
What’s already clear is that the era of competing streaming services fragmenting audiences across multiple platforms is winding down. Skydance’s move, combined with similar consolidations elsewhere, points toward a market that will resemble cable in structure — fewer, larger, bundled — rather than the chaotic free-for-all of the past decade.
Consumers who wanted unlimited choice across dozens of platforms may need to adjust their expectations. The trade-off is simpler access, stronger recommendations, and potentially fewer bills. The risk is less variety, higher prices, and less incentive for any single platform to take creative chances on unusual or ambitious projects.
The streaming wars aren’t ending because streaming lost. They’re ending because the math stopped working, and consolidation is the only path that does.